Quick answer
Roof insurance claim help in Cleveland, OH. Free damage inspection, photo documentation, adjuster meetings and supplements written against the carrier price list. Call (330) 918-1018.
- Local conditions: Cleveland doubles and century homes often still run built-in box gutters, which behave nothing like a hung K-style run and fail differently when they ice.
- Service area: Cleveland and Cuyahoga County. Direct line (330) 918-1018.
- Documentation: written scope up front and photographs throughout, which is what an adjuster needs.
- Licensing: licensed Ohio contractor — permits pulled and inspections scheduled as part of the job.
Do I actually have storm damage?
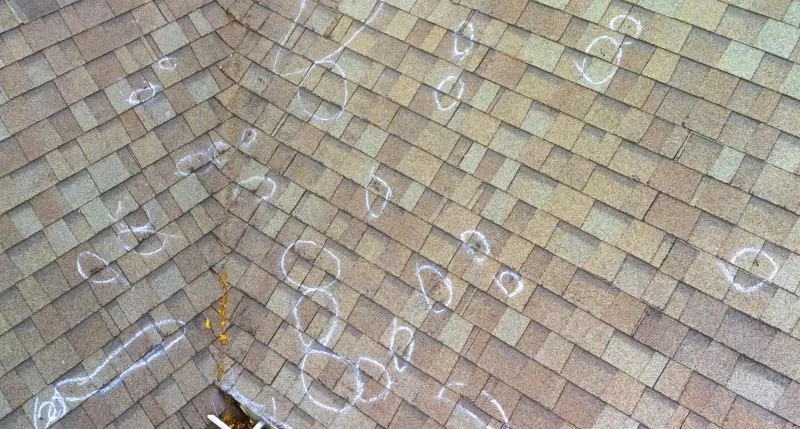
Hail and wind damage is frequently invisible from the ground, which is why so much of it goes unclaimed until the roof starts leaking years later. What an adjuster is looking for:
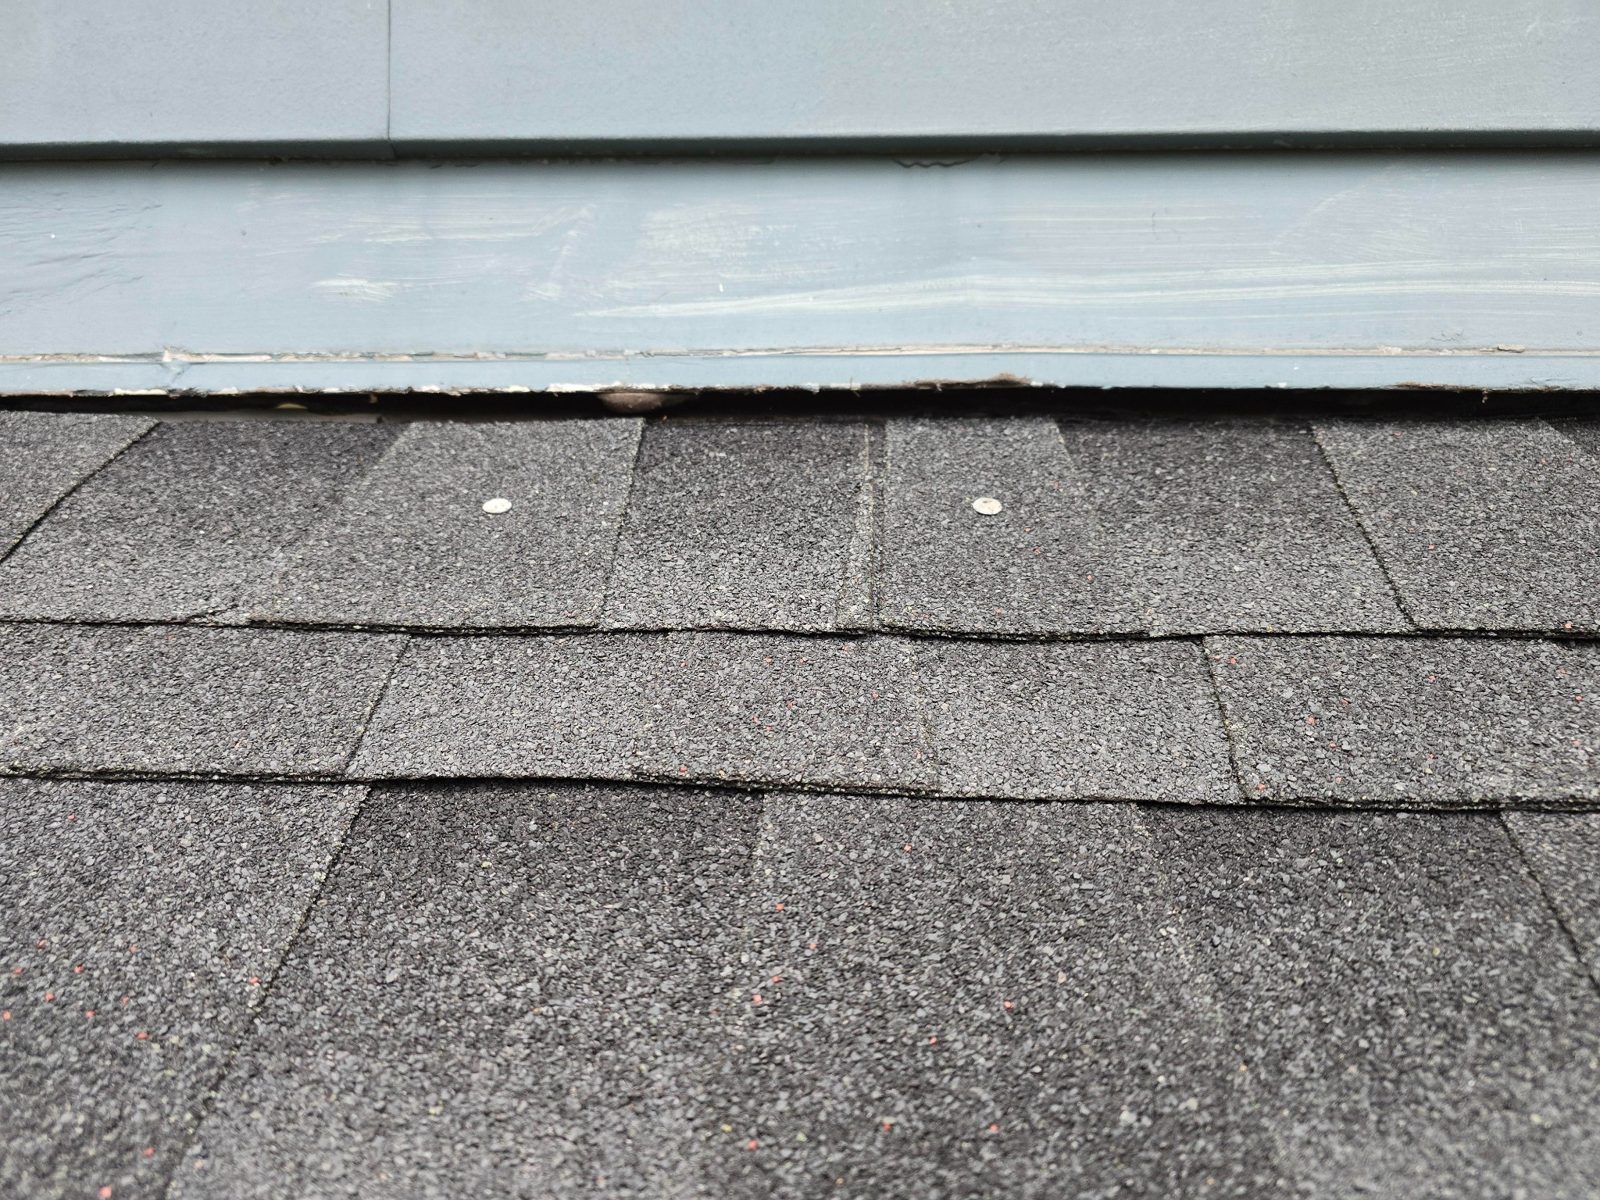
- Hail bruising — soft spots where the mat is fractured and granules have been knocked loose. Roughly 1 inch hail and up will bruise an asphalt shingle; smaller stones can still damage soft metals.
- Creased shingles from wind lift — the crease breaks the mat even when the shingle lays back down.
- Granule accumulation at downspout outlets after a storm.
- Collateral evidence — dented gutters, soft metal vents, damaged fascia, dinged siding. Adjusters use these to date and confirm the event.
We inspect free and tell you straight whether there is a claim worth filing. Filing without damage helps nobody.
How does the claim process actually run?
- Inspection and documentation — we photograph every elevation and every damaged component before anything is filed.
- You file the claim with your carrier. We never file on your behalf, and no contractor should.
- Adjuster meeting — we meet them on site with our documentation so nothing gets missed while they are up there.
- Scope review — we compare their estimate against what the job actually requires and what code requires.
- Supplement — missed line items are submitted against the carrier price list, with photographs and code citations.
- Work and completion — then depreciation is released once we certify completion.

ACV, RCV and depreciation — what do they mean for your cheque?
On a replacement cost policy the carrier pays in two parts. The first cheque is actual cash value, which is the replacement cost minus depreciation and minus your deductible. The recoverable depreciation is held back and released after the work is finished and documented.
That is why a first cheque looks alarmingly small, and it is why completion documentation matters — the withheld amount is yours only if the work is completed and certified, usually within a deadline stated in your policy. On an actual cash value policy there is no second cheque, so knowing which you have before you start matters.
We are a contractor, not a public adjuster or your carrier. Coverage decisions are made by your insurer under your policy language.

Storm damage inspection near Cleveland — free and documented
Free inspection with photographs. You keep the documentation whether or not you file, and whether or not you hire us.
Recent storm? Call (330) 918-1018. Damage is easiest to attribute to an event while it is fresh, and policy clocks start on the date of loss.
Back to Cleveland services or all Ohio locations.