A creased shingle is a broken shingle — and insurance owes for broken. We find every qualifying crease, tab, and tear, document it properly, and run the claim so you pay only your deductible.
Before we price Wind Damage Claims Done Right, we look at depreciation, the scope of loss and line-item pricing — the details that decide how long the work holds. You get a photographed assessment and a written scope with no obligation, and if the cause traces to a storm we document it for your carrier. Licensed and insured in Ohio, Pennsylvania and New York.
Water damage gets worse every hour — call nowWind Damage Claims — priced in writing before we start, no obligation.
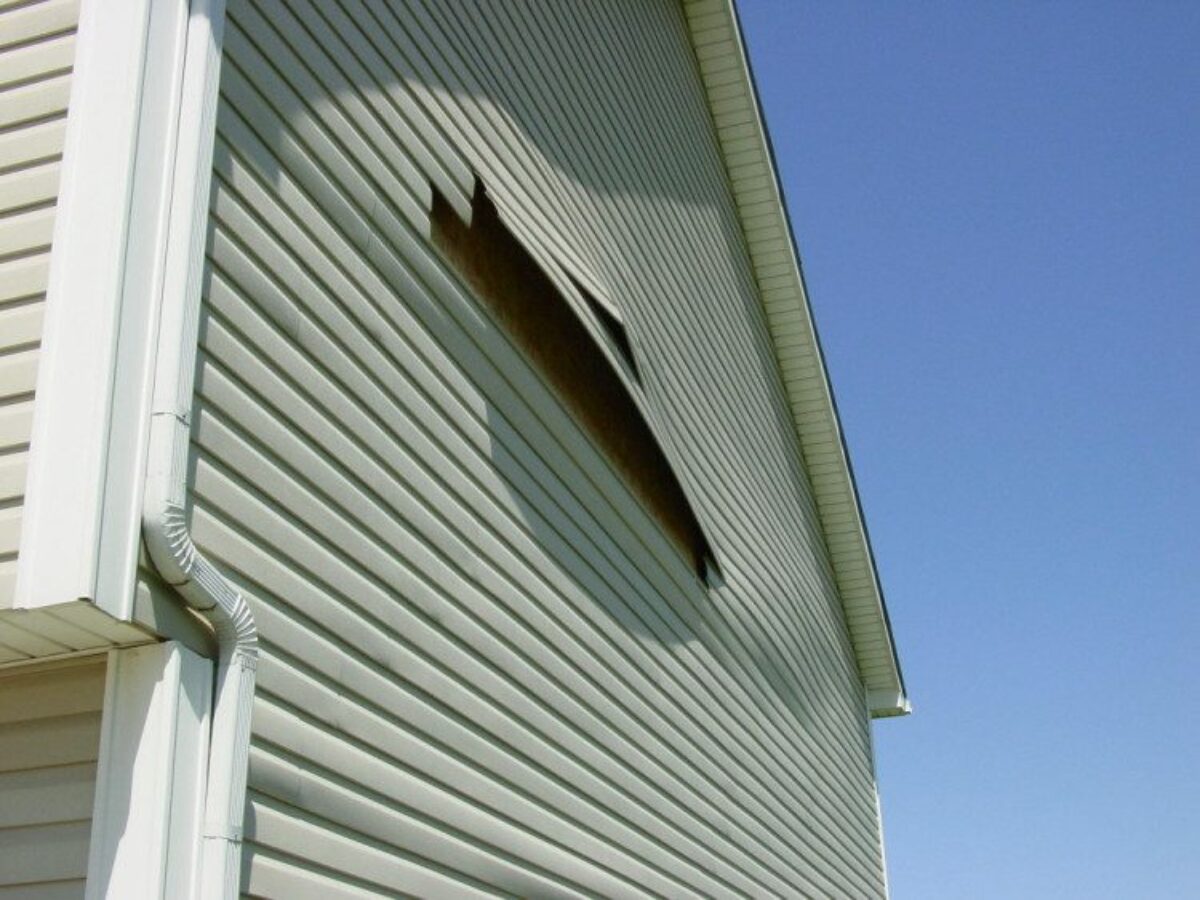
Wind damage often shows as creased or lifted shingles, missing tabs, a broken seal strip that lets shingles flutter, and displaced ridge cap. Much of it is not visible from the ground, and a lifted shingle that has resealed may still have a broken bond, which is why wind damage is frequently underestimated. Related: storm damage claims and roof insurance claims.

Missing tabs and exposed decking are the obvious part. The part homeowners — and rushed adjusters — miss: creased shingles. When wind folds a shingle back, the mat fractures at the crease; it may lie flat again, but it’s broken and cannot seal. Creases mean those shingles are damaged, and when your shingle is discontinued with no match available, repair stops being an option — which is how wind claims become full replacements.
Free inspection with every qualifying crease and tab photographed and mapped. We help file, then meet your adjuster on the roof so nothing gets waved off from the driveway. If the estimate comes back short — they often do — we supplement with photos, measurements, and code citations until the scope is right. On approved claims you pay your deductible and we build the rest.


Gusts in the 50–60 mph range routinely crease and lift shingles — and aging or marginally sealed shingles go earlier. If a storm made the news, roofs in its path have qualifying damage.
Yes. Creases don’t show from the ground, and they’re the most commonly missed qualifying damage. The inspection is free and takes half an hour.
That’s where supplements come in. If creased shingles were missed, or your shingle is discontinued and can’t be patched with a match, we document it and push the scope to what the policy actually owes.
Weather claims are not-at-fault claims and typically don’t trigger the increases at-fault claims do — your agent can confirm specifics for your policy.
Gusts in the 50–60 mph range lift and crease aging shingles; certified-installed architectural shingles carry ratings far higher — age and installation decide the threshold.
Creased tabs that fold back, missing shingles, lifted edges with broken seal strips — and horizontal crease lines across storm-facing slopes.
Usually is — creases read at roof level by hand and angle light. Ground-level ’looks fine’ is how wind claims expire unfiled.
Broken seal strips are compromised even when tabs lie flat — documented properly, seal damage is legitimate claim scope.
The exterior works as one assembly — these are the pieces that connect to this one.
Policies require prompt notice, and many carriers apply a filing window…
Learn more →Most policies cover sudden, accidental damage from a specific event such…
Learn more →Damage from a covered event is generally included, but siding claims…
Learn more →Tarping is temporary stabilization that stops active water intrusion until permanent…
Learn more →Gutters damaged by a covered event are generally part of the…
Learn more →Hail damage on asphalt appears as random soft-bruise impacts with granule…
Learn more →Wind Damage Claims is available across our licensed service territory in Ohio, Pennsylvania and New York. Find your city below, or call (330) 918-1018.
Every crease photographed, the whole claim handled — you pay your deductible.
Takes about 20 seconds.
