The insurance company has adjusters, software and lawyers. You have us. Free inspection, claim filed, adjuster met on your roof, supplements fought — and the restoration done right.
Before we price Insurance Claims, we look at the scope of loss, line-item pricing and depreciation — the details that decide how long the work holds. You get a photographed assessment and a written scope with no obligation, and if the cause traces to a storm we document it for your carrier. Licensed and insured in Ohio, Pennsylvania and New York.
Water damage gets worse every hour — call nowInsurance Claims — priced in writing before we start, no obligation.
A restoration contractor documents the damage, prepares a scope of the work actually required, and supports supplements when the approved scope misses items the repair needs. The contractor does not adjust the claim. The value is in evidence: photographs, measurements and code citations that let the carrier evaluate the full scope. Related: chimney services and commercial roofing, gutters & winter roof services.
If weather did it, we’ve claimed it. Tap a damage type to see the related service — from roofing and gutters to nationwide ice dam response.
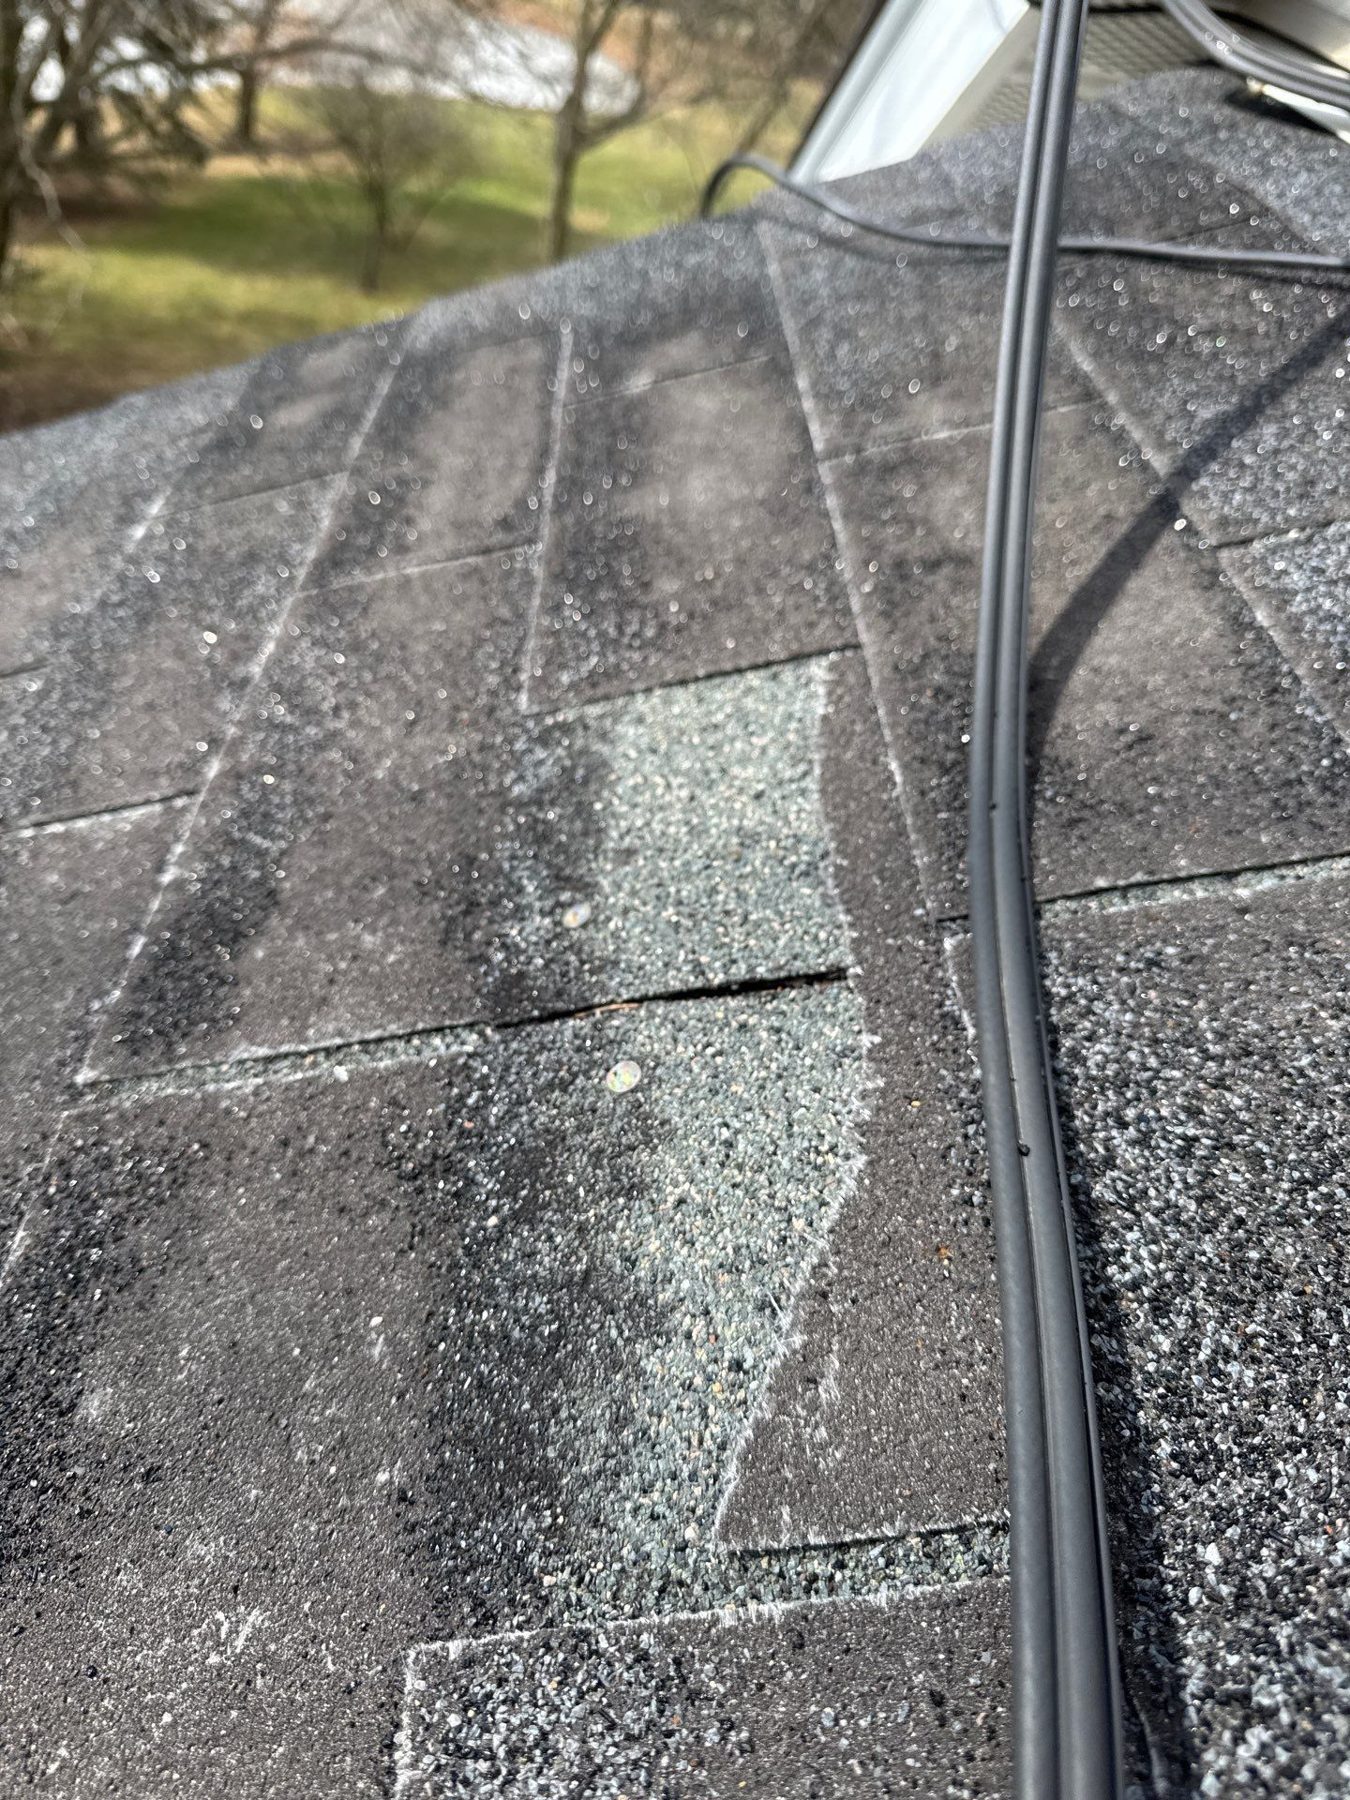 Hail
Bruised shingles, cracked mats, dented vents and gutters. Hail damage is easy to miss from the ground — and carriers count on that. We photograph every impact.
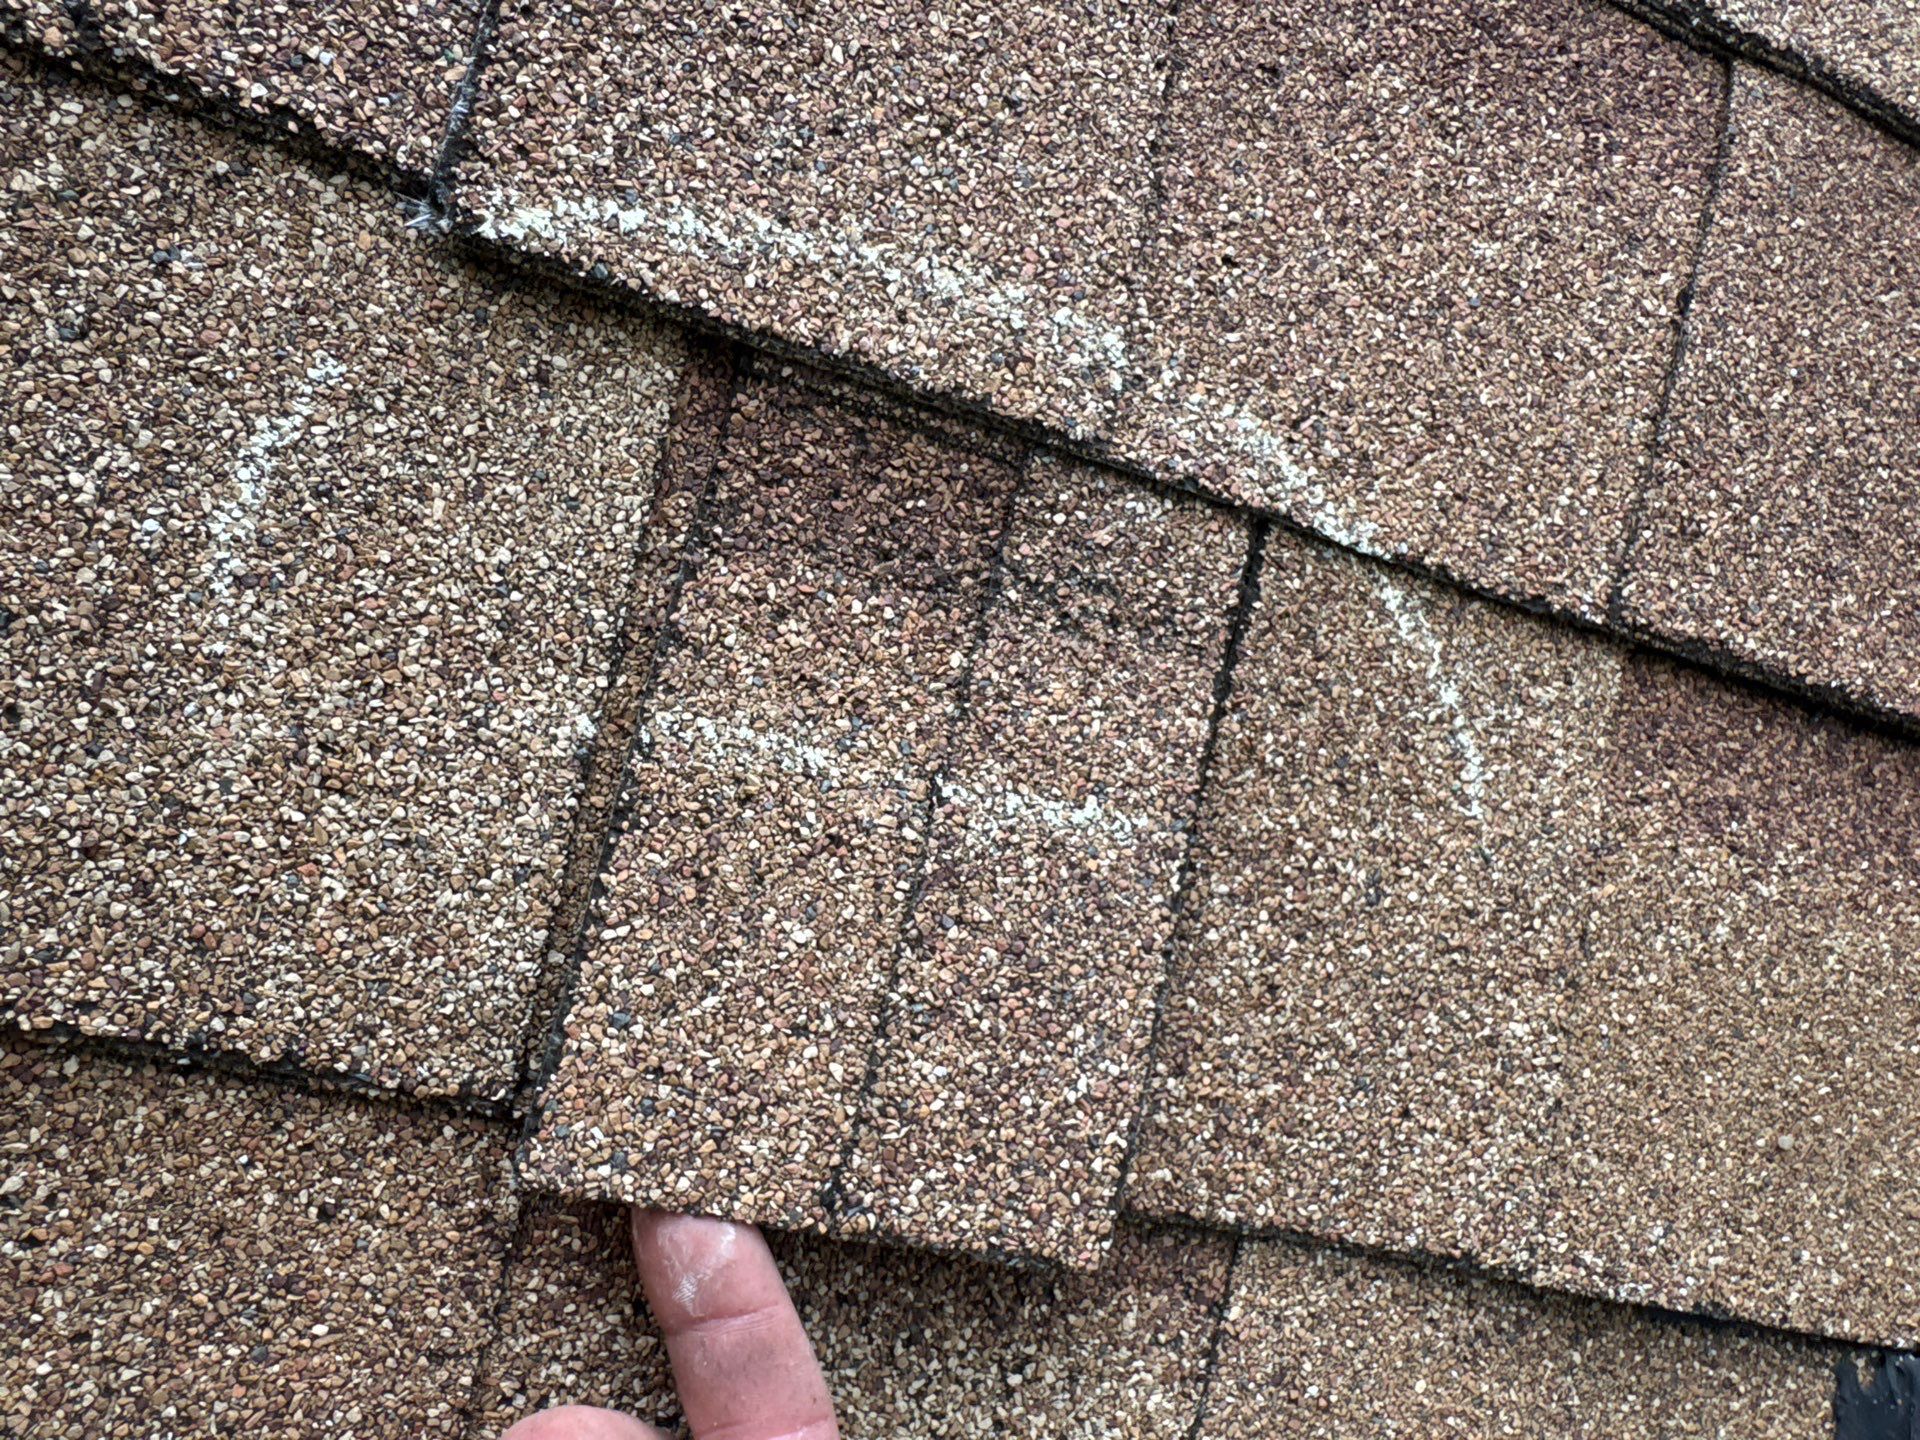 Wind
Creased, lifted or blown-off shingles — even one creased shingle can qualify a roof when matching shingles are discontinued.
 Winter
Water backing up under shingles into ceilings and walls. Most policies cover the interior damage — we document it and handle the claim.
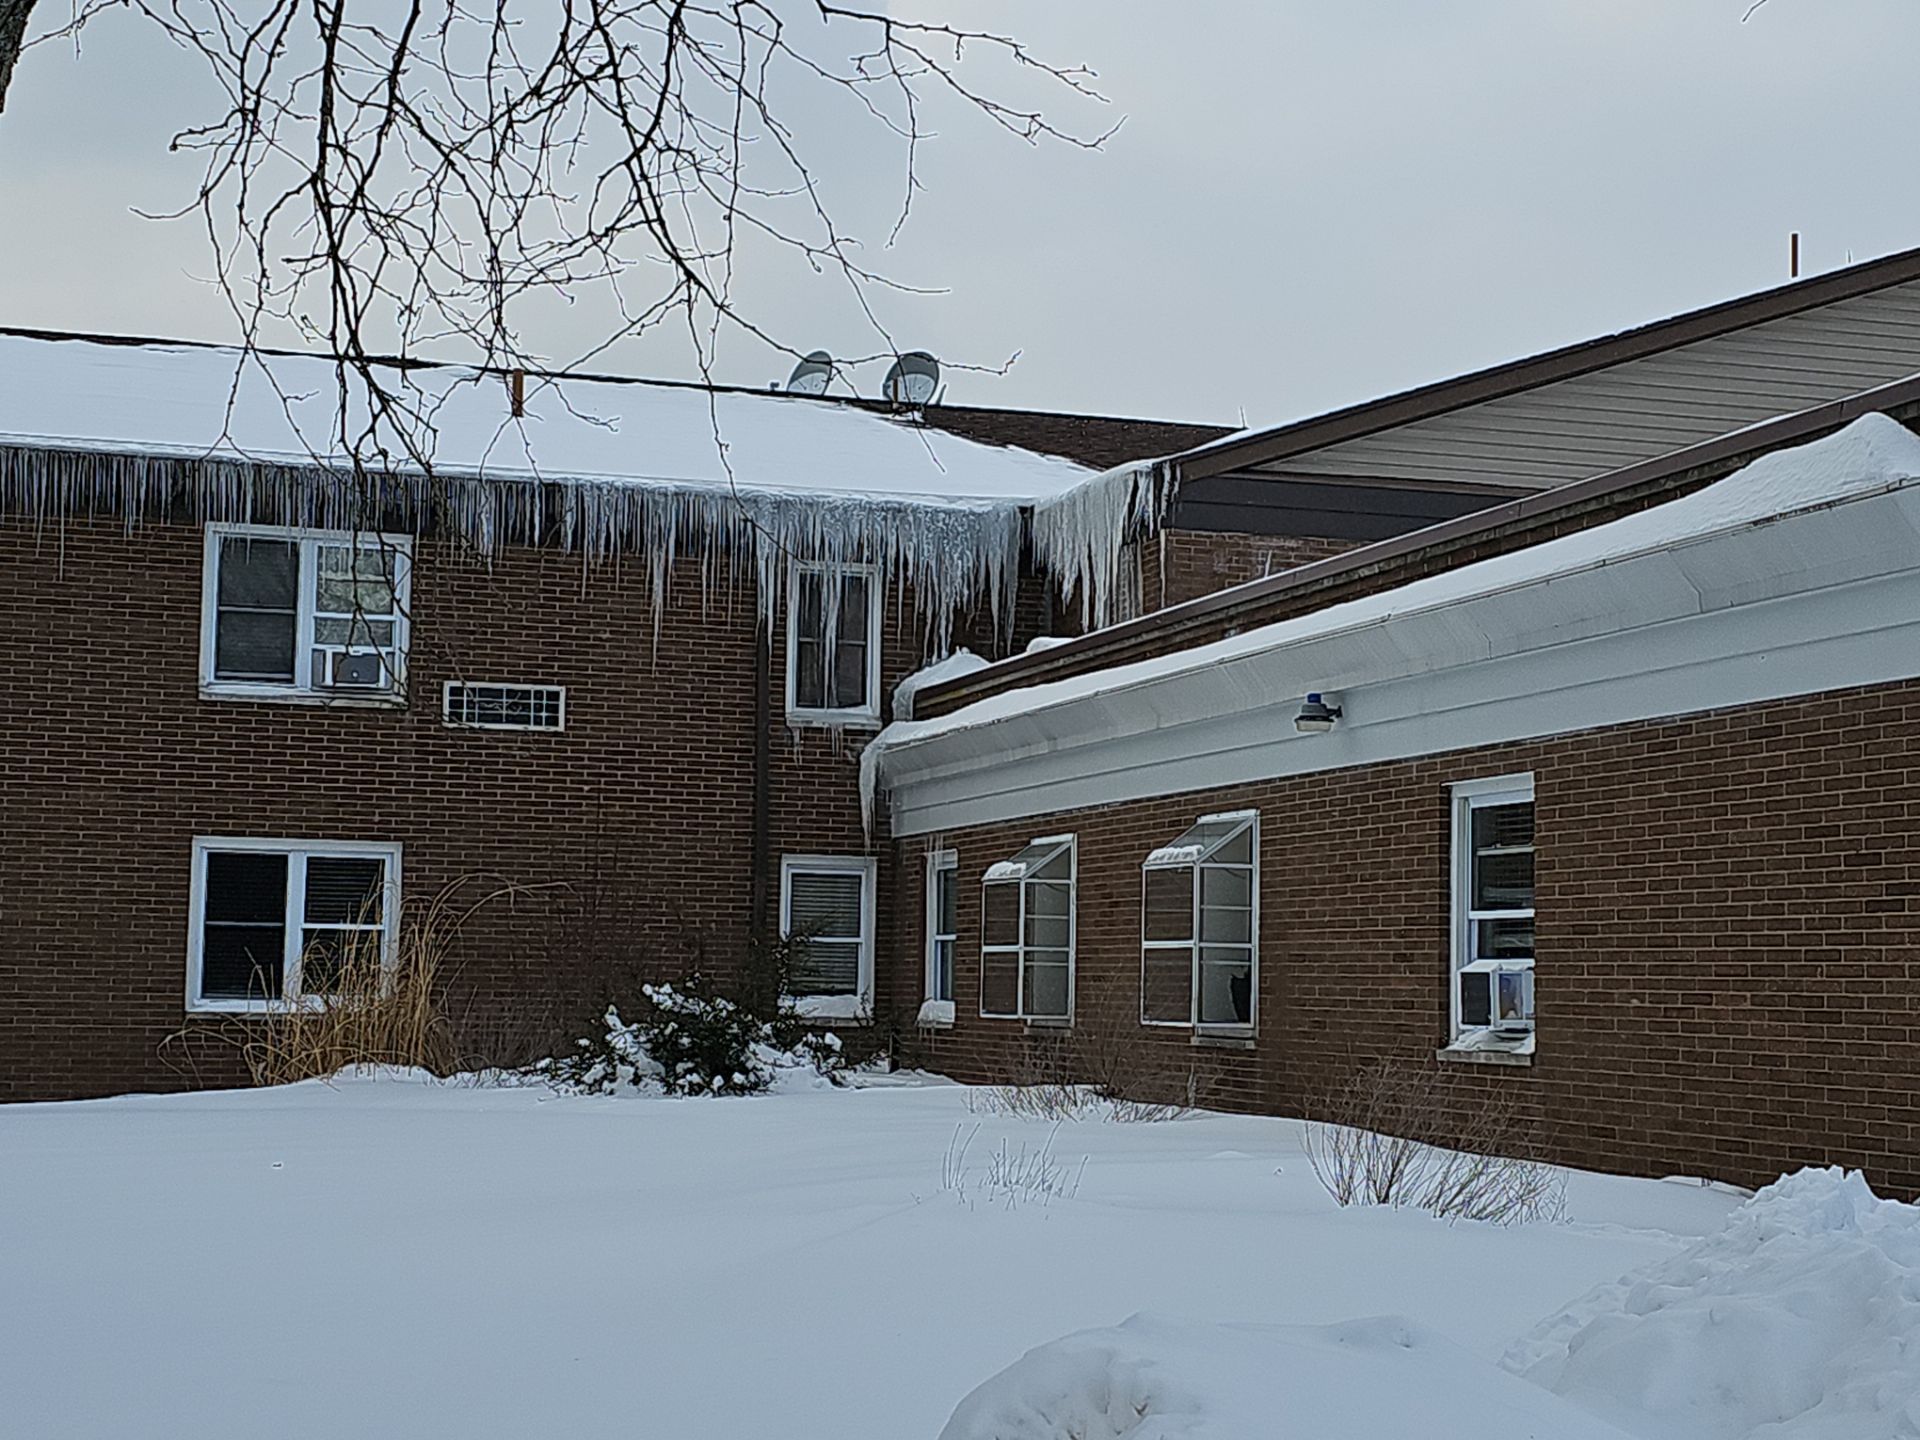 Attic
Soaked insulation, ceiling stains, mold-prone condensation from ice dam backups and roof leaks. We inspect the attic, map the moisture, and claim every damaged layer.
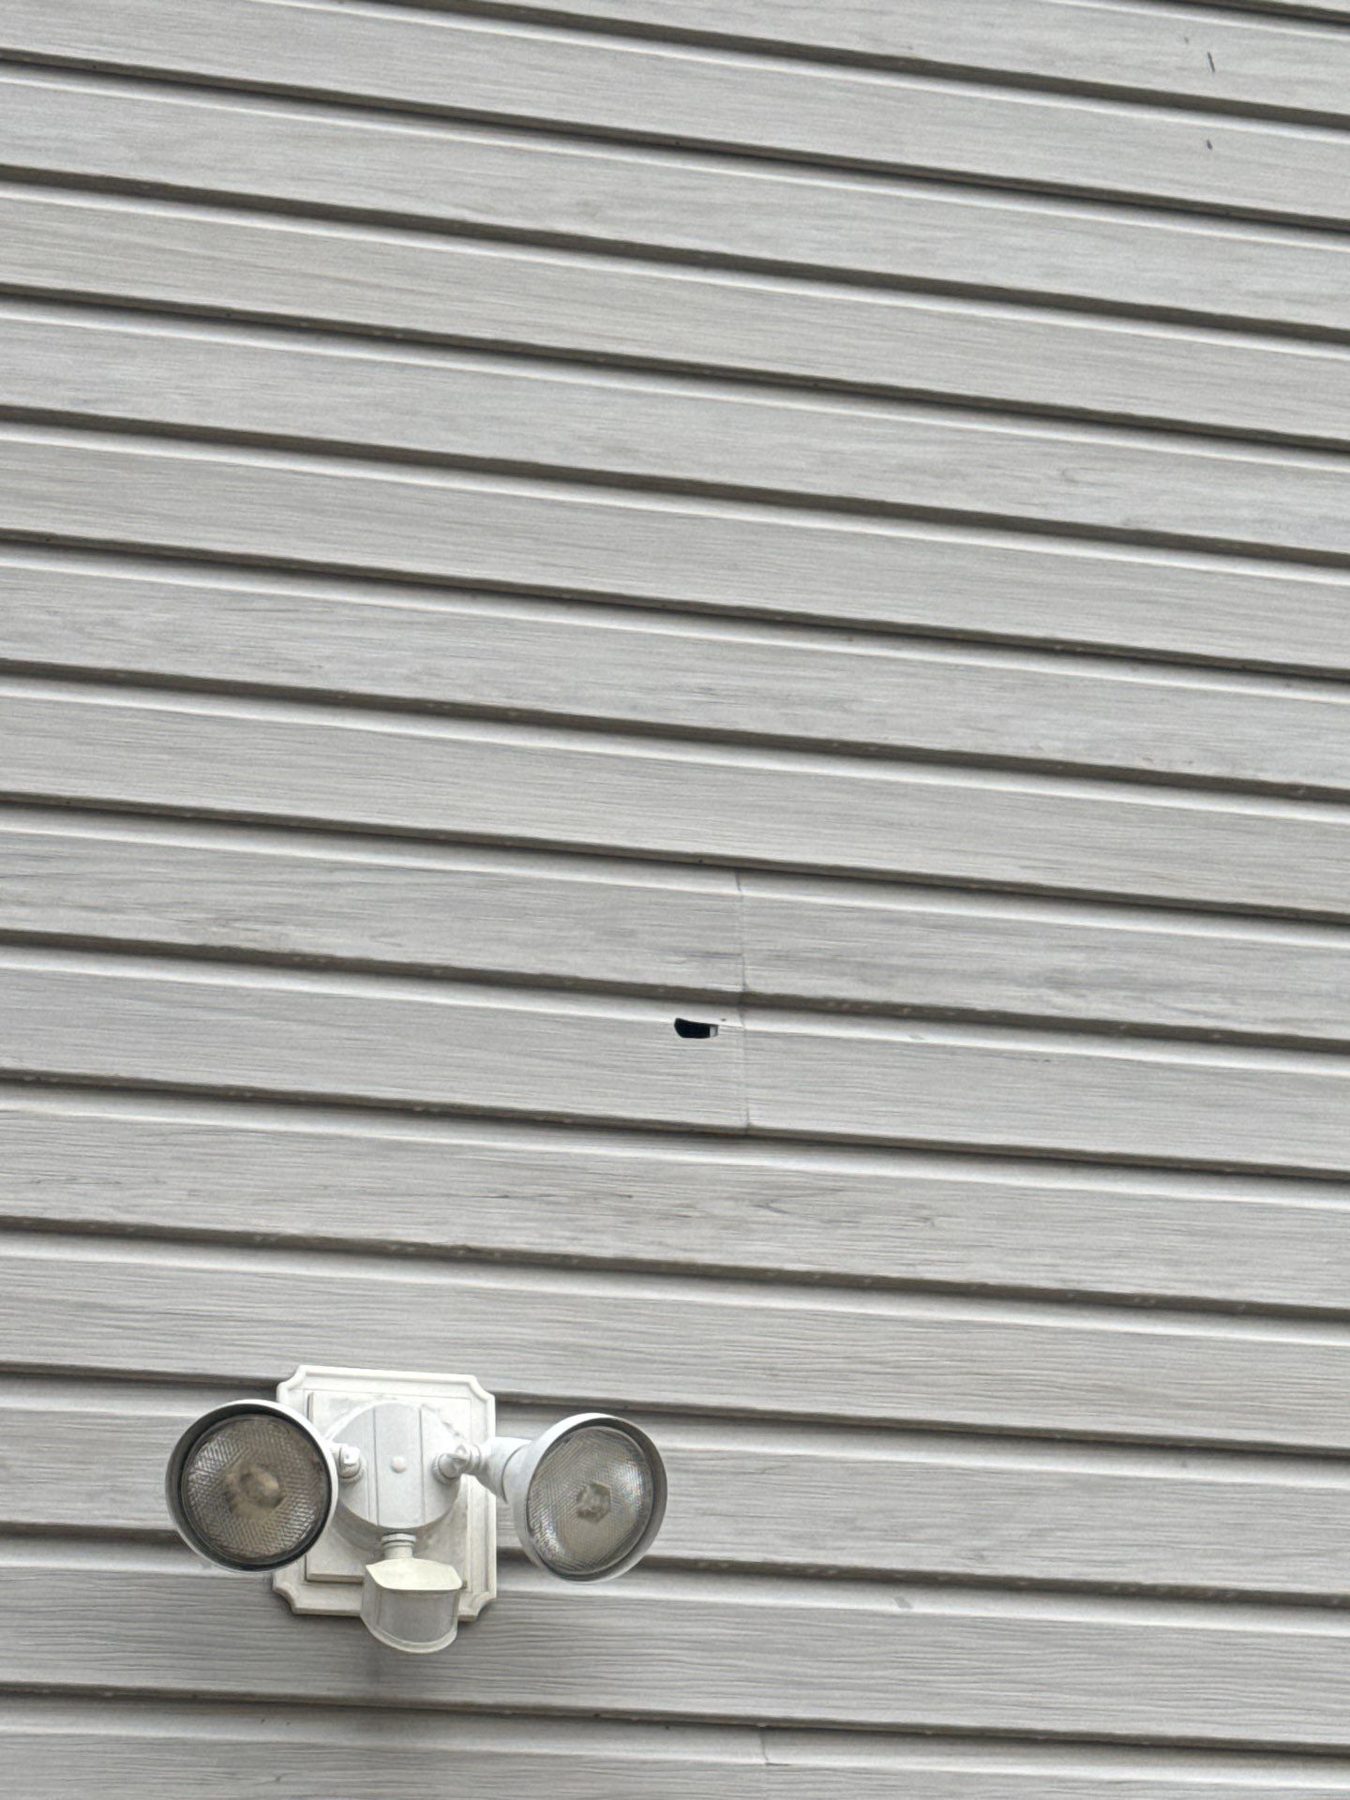 Siding
Cracked, holed or blown-off panels. When your siding is discontinued, matching rules can get the whole elevation — or the whole house — replaced.
 24/7
Fallen trees, punctures and active leaks. We tarp first to stop the damage, then document everything for the claim while it’s fresh.
Roof, siding, gutters and attic — every impact photographed and measured before anyone talks to the carrier.
We help you open the claim correctly — the wording and documentation at this step decide how the whole claim goes.
We’re on the roof with the adjuster, pointing at every qualifying damage — so nothing gets “missed.”
We build to code and supplement the carrier with code citations when the approved scope falls short. You pay your deductible.
Two real claims, start to finish. Small-looking damage — six-figure and five-figure payouts.
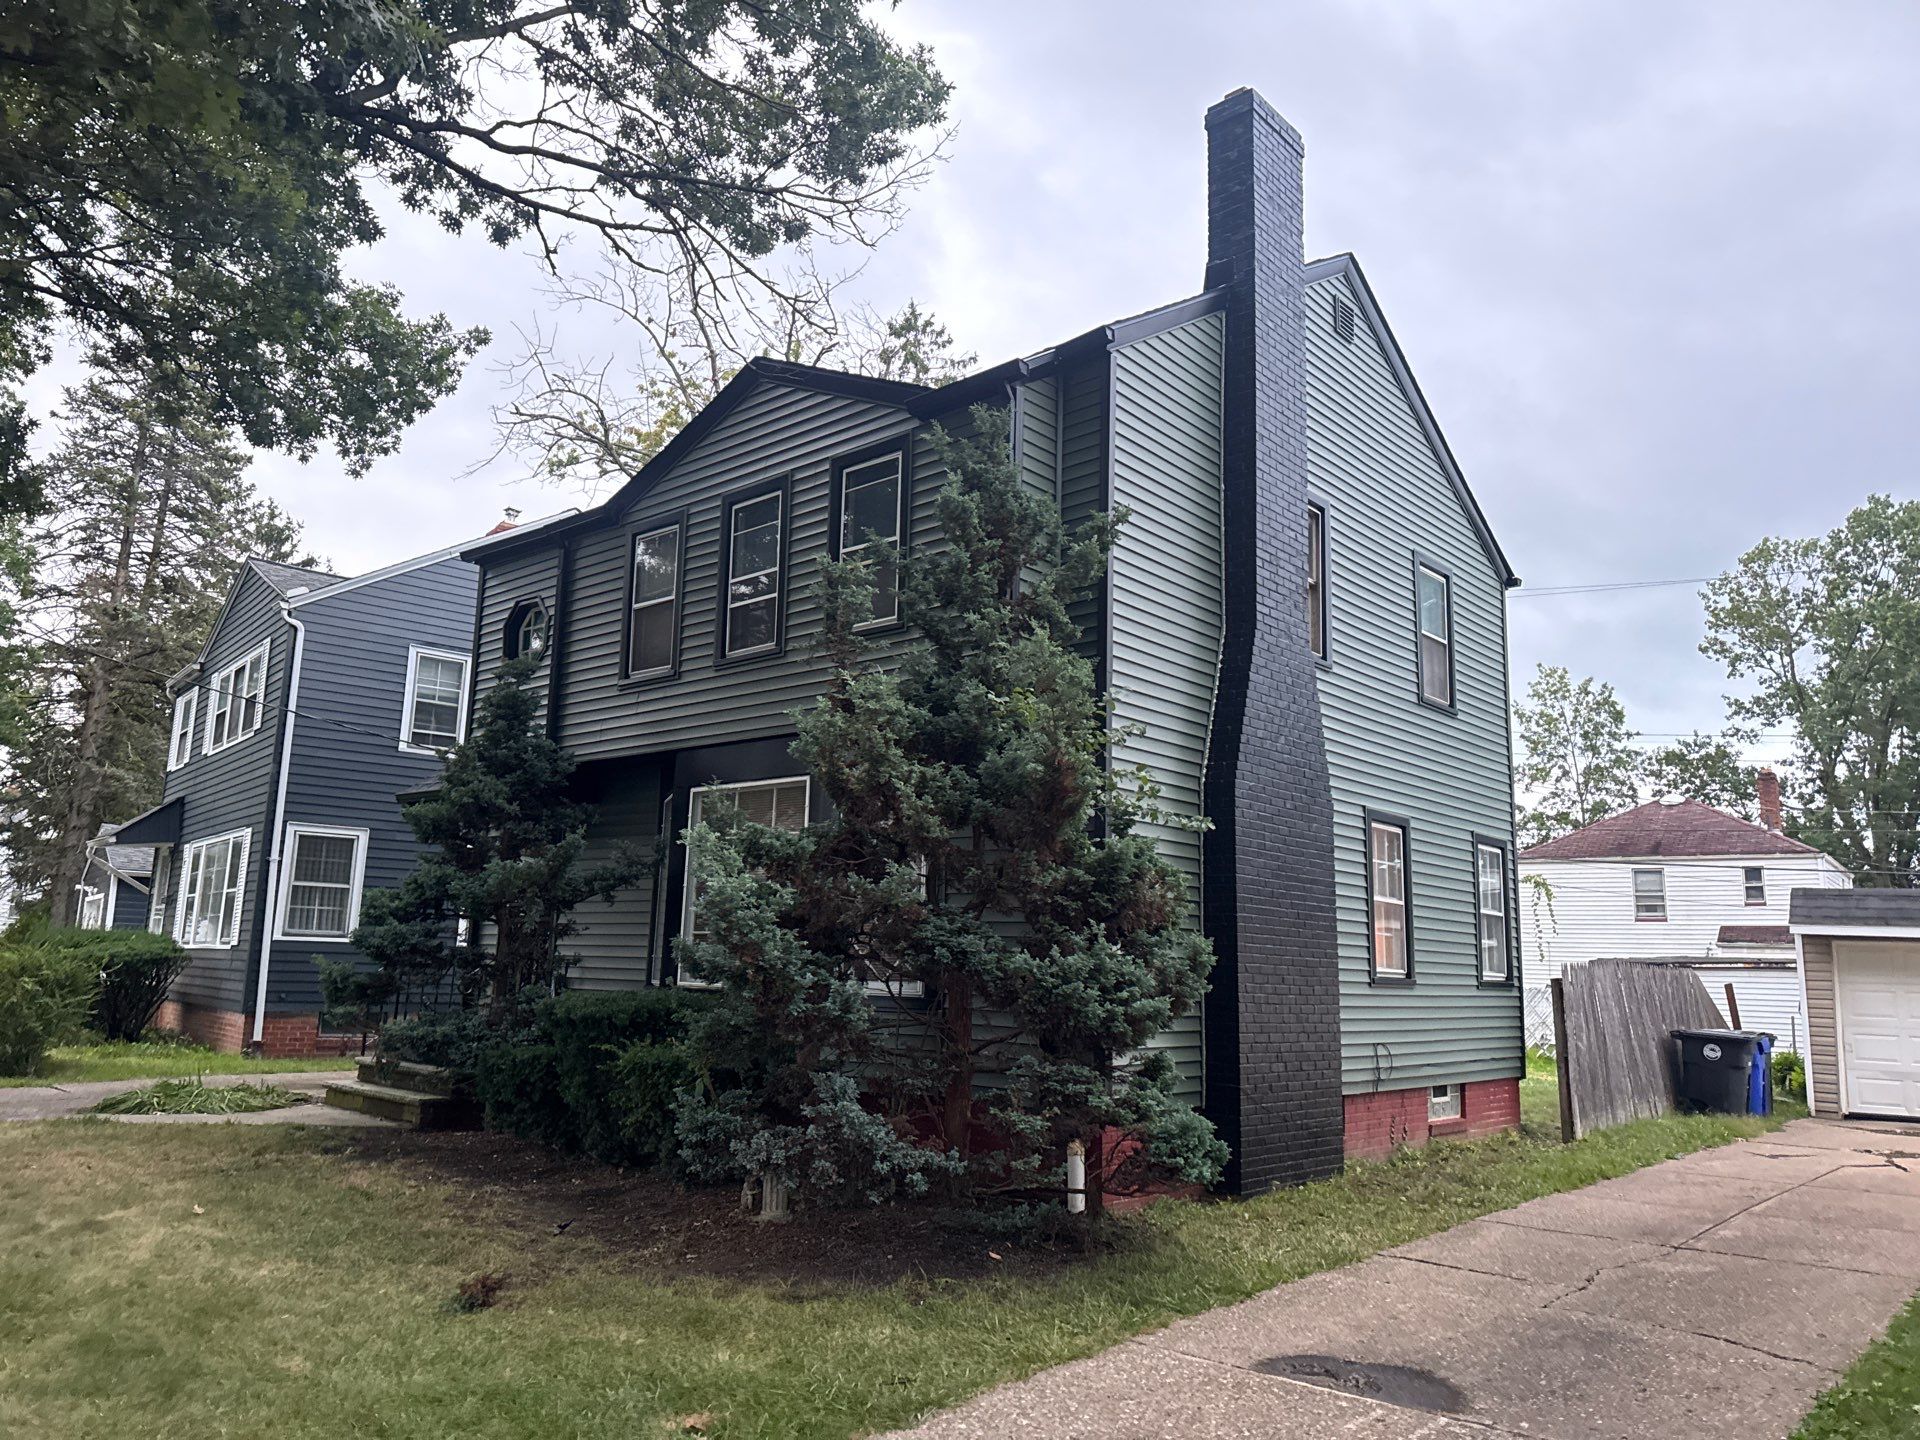
After the storm, the homeowner saw a few damaged shingles and some marks on the siding. It looked like a minor repair. The siding hail hits were about 20 feet up — clear to see and easy to prove. We came out for a free inspection and photographed every impact.

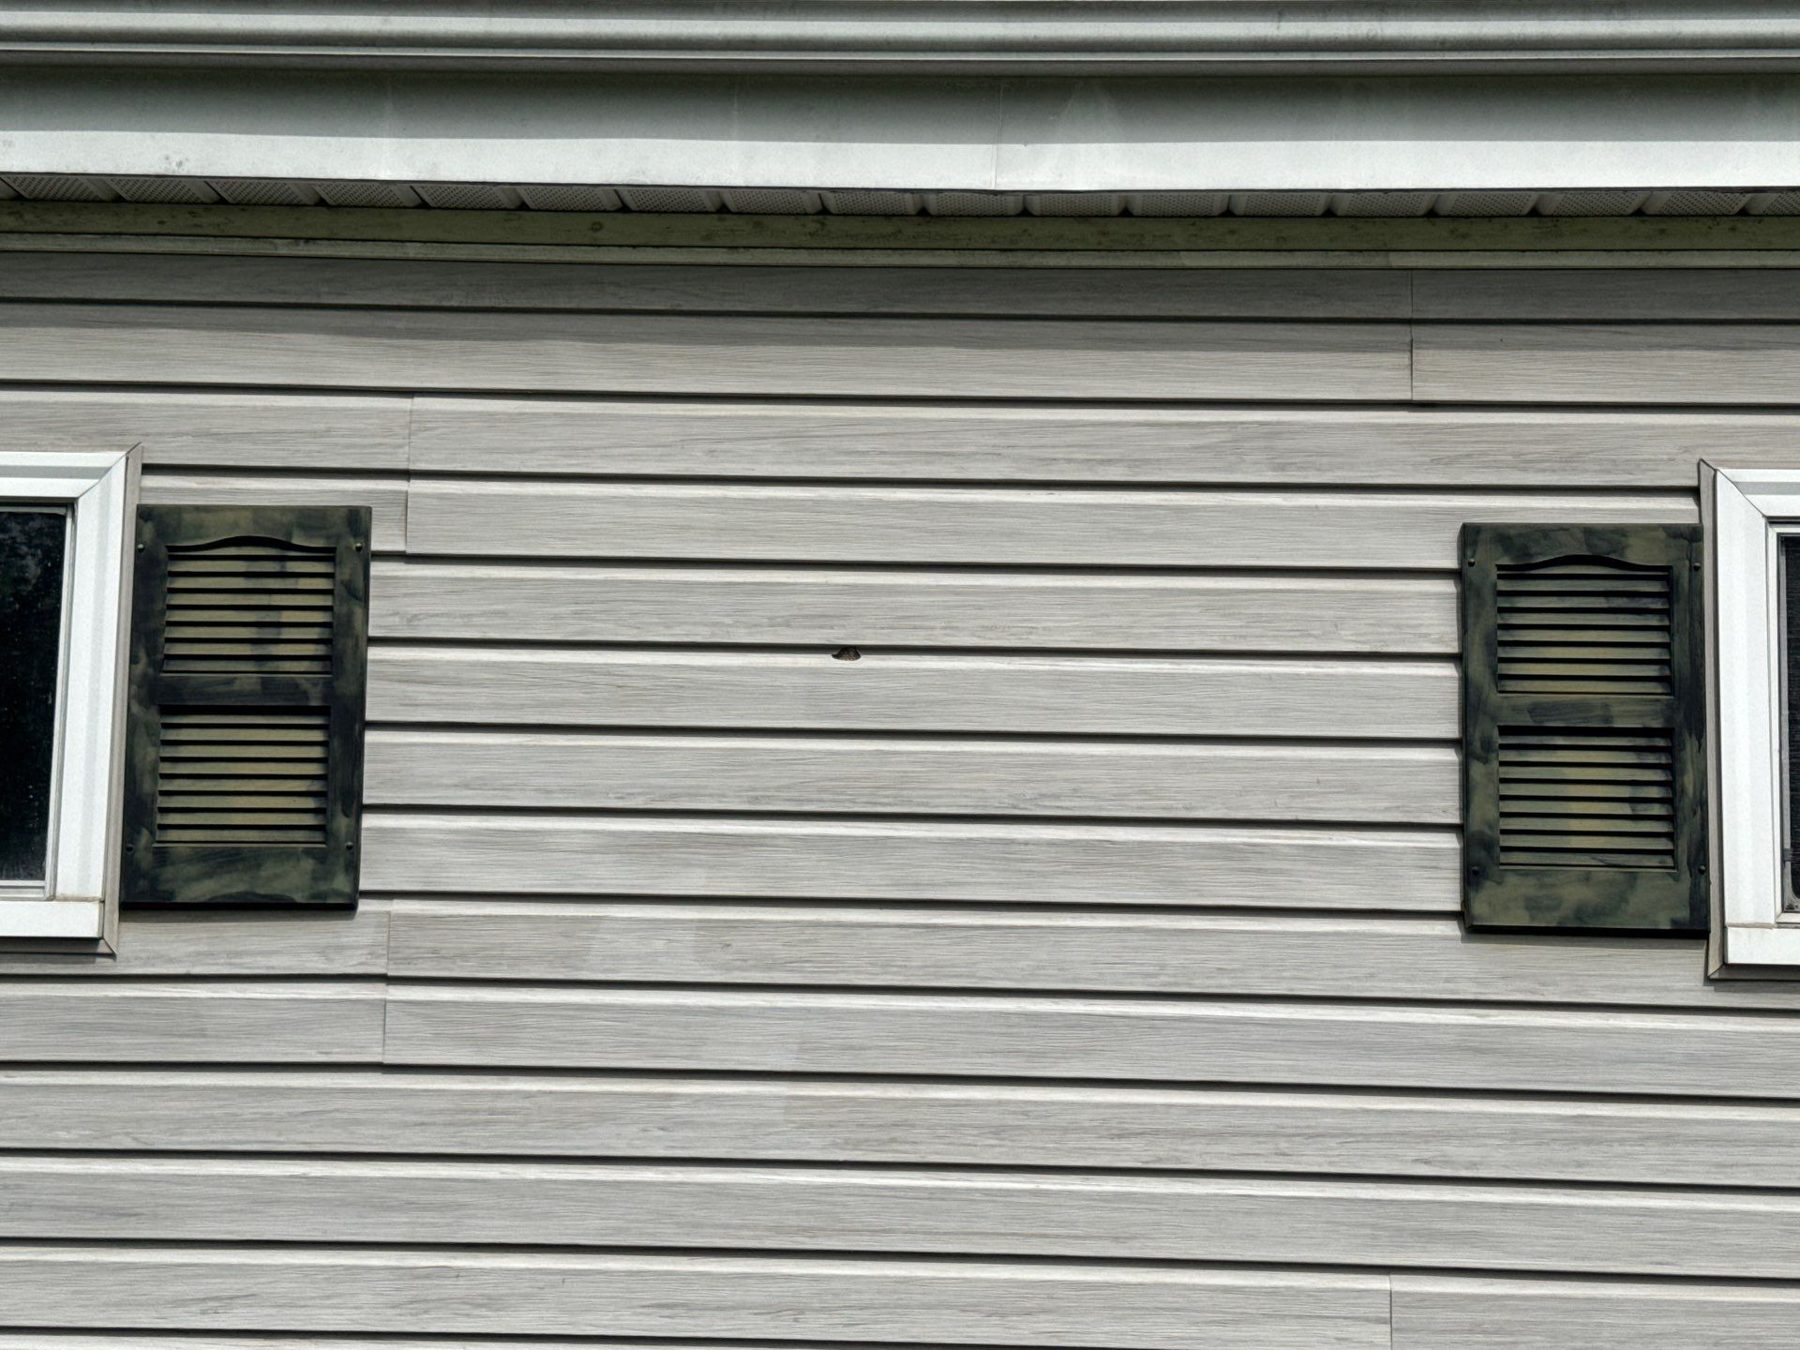
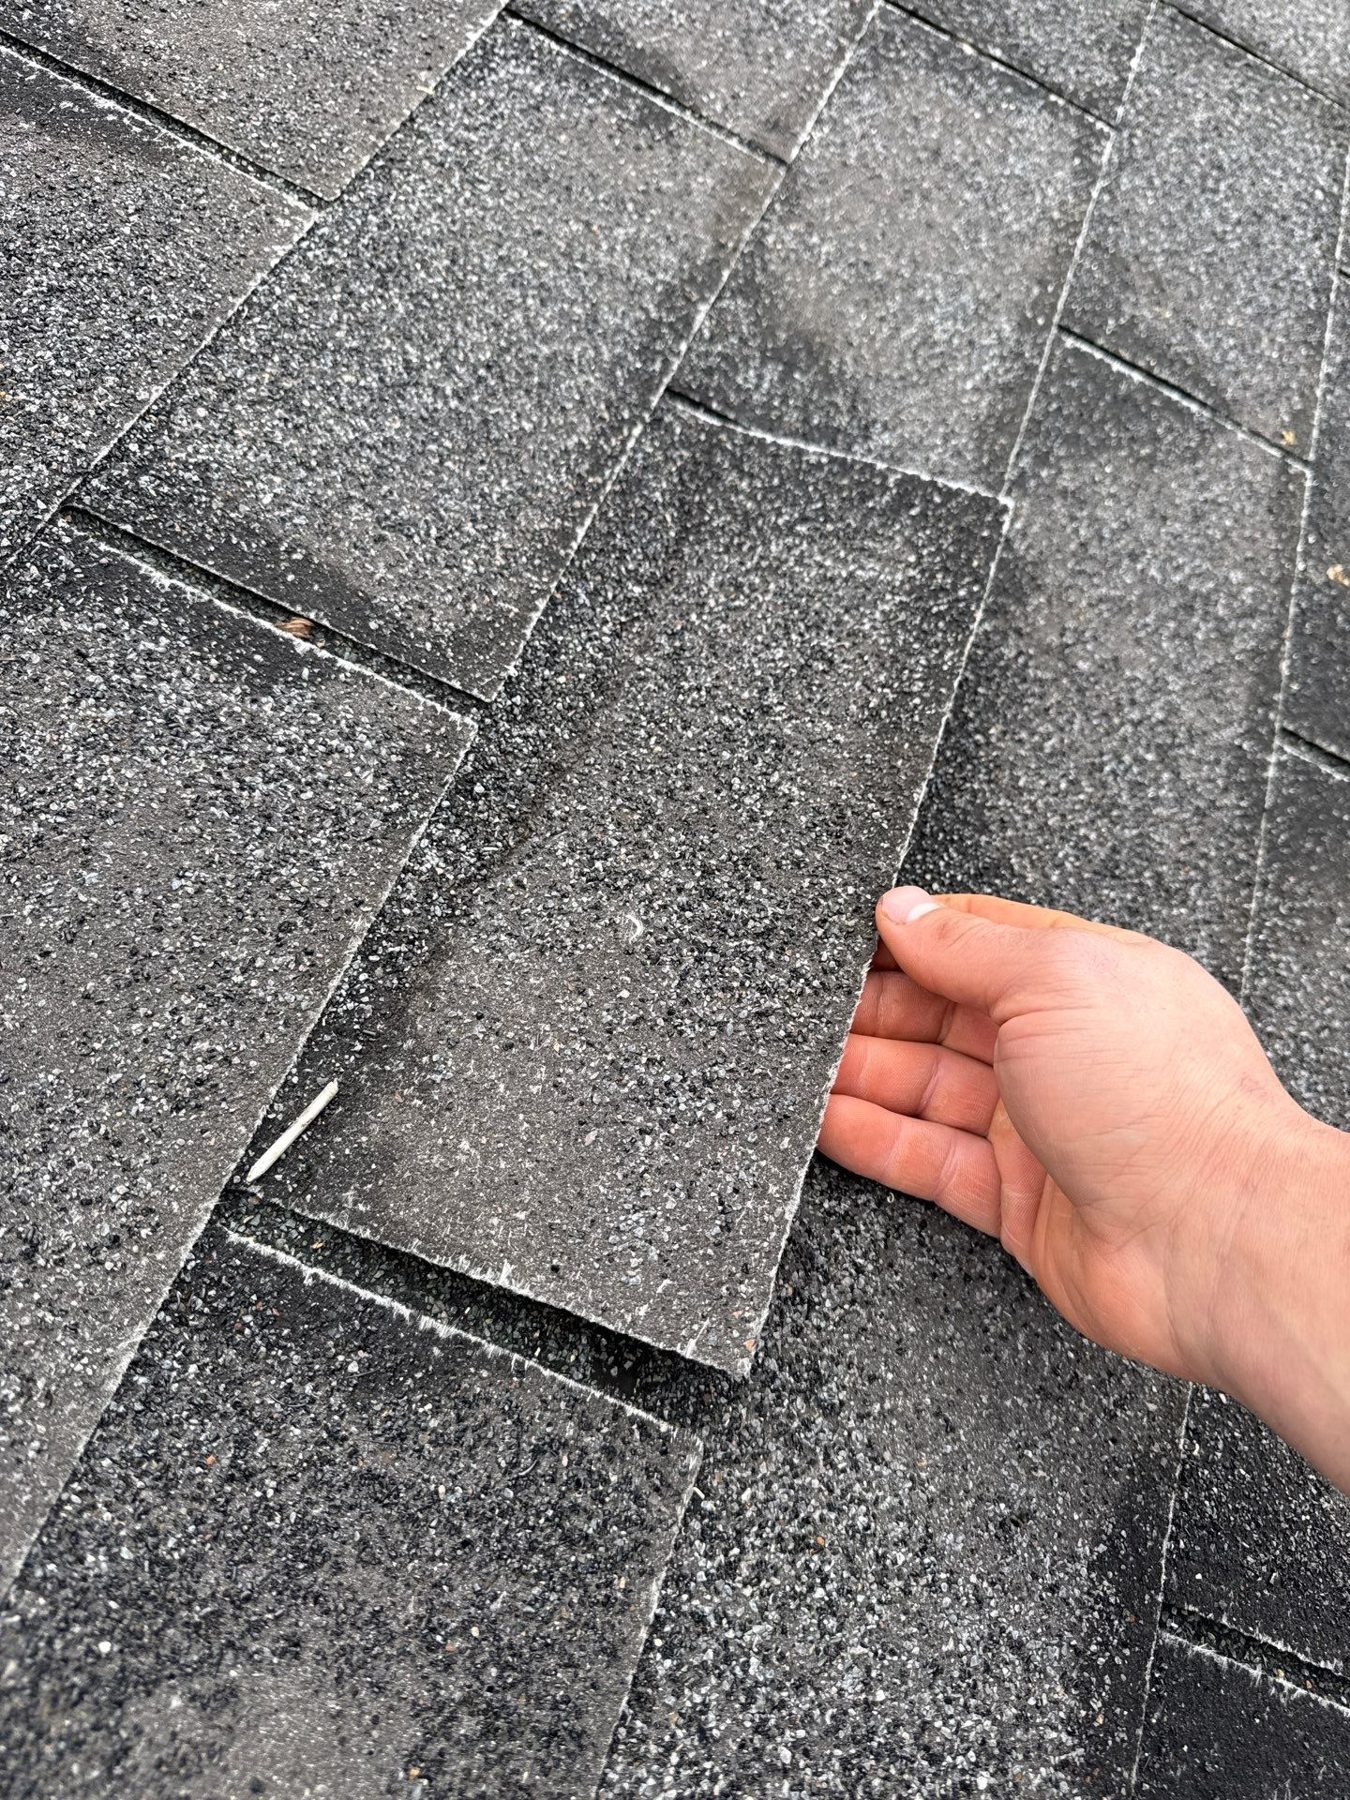
We met the adjuster on-site and walked the whole property with them. The shingles were discontinued — no match could be found. That meant patching was not an option. Insurance approved a full replacement of the house and the garage.
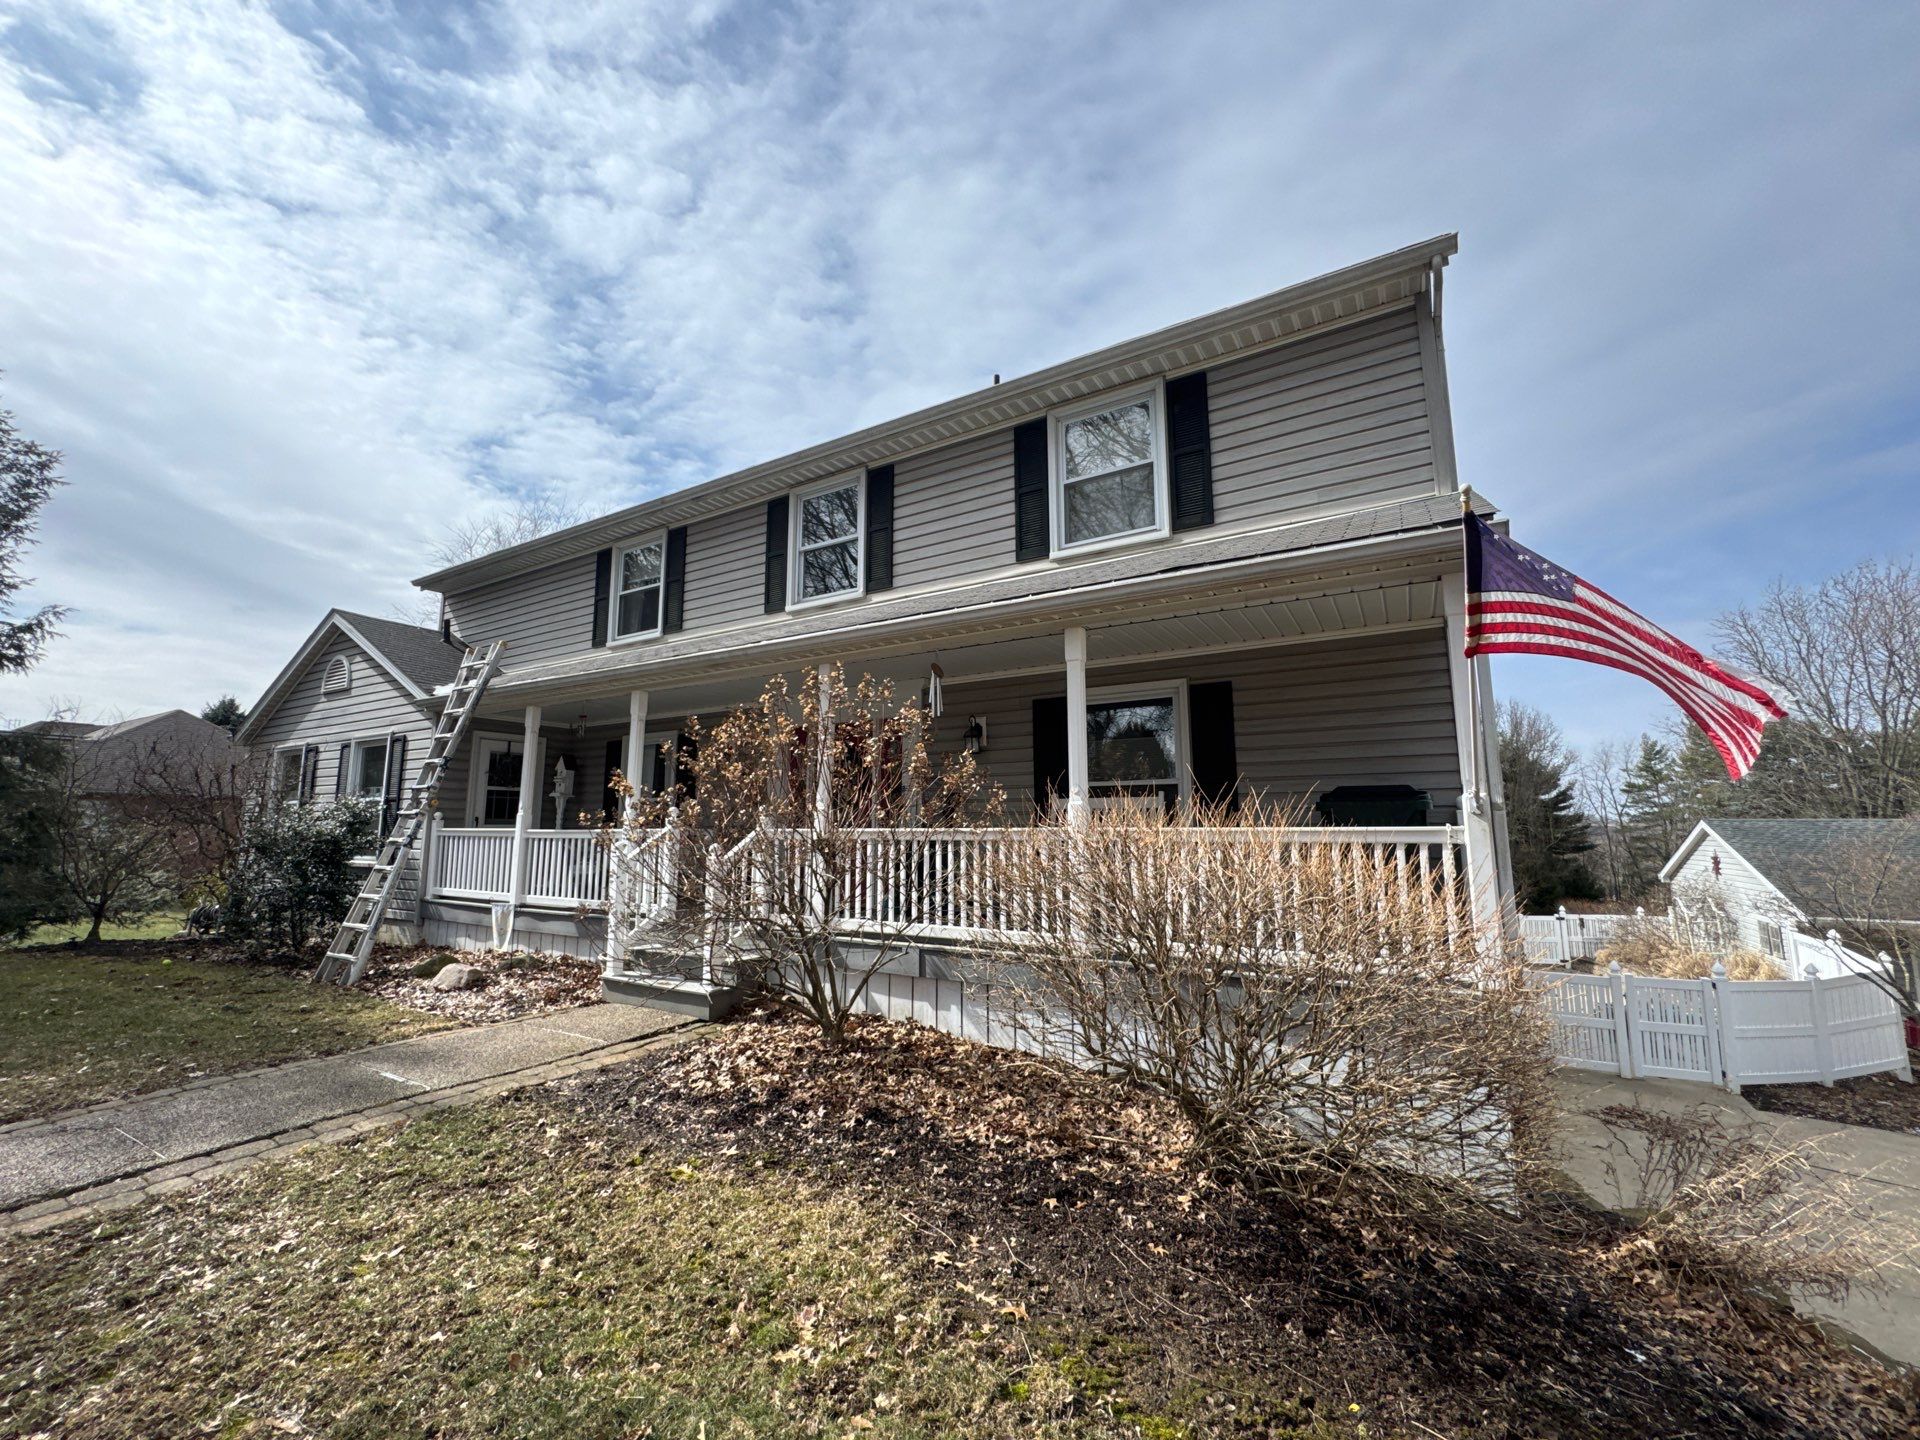

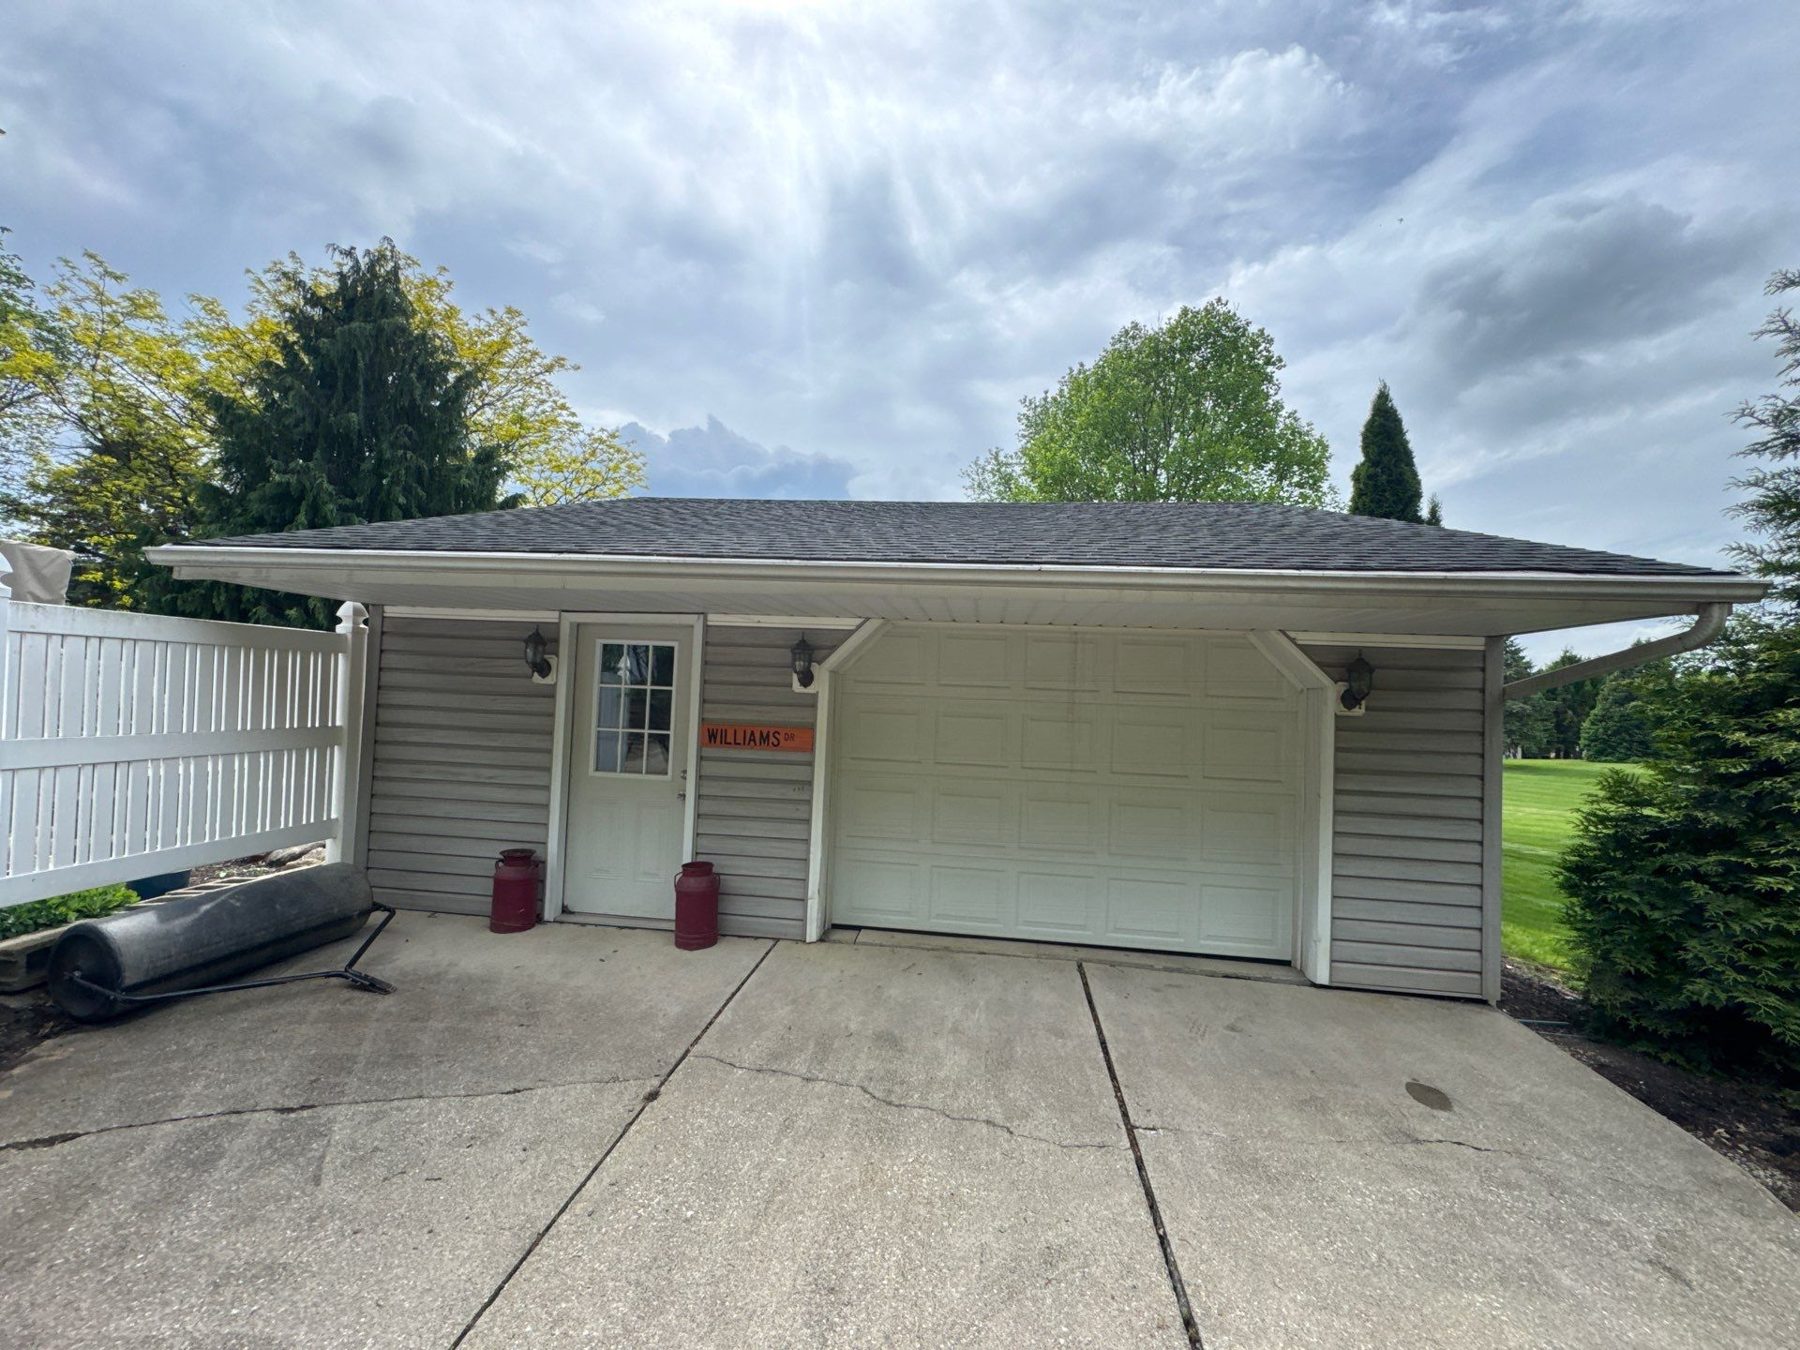
Our crews replaced the roof, the siding, and the gutters on the house and the garage. The homeowner did not lift a finger — we handled the claim paperwork, the supplements, and the build.

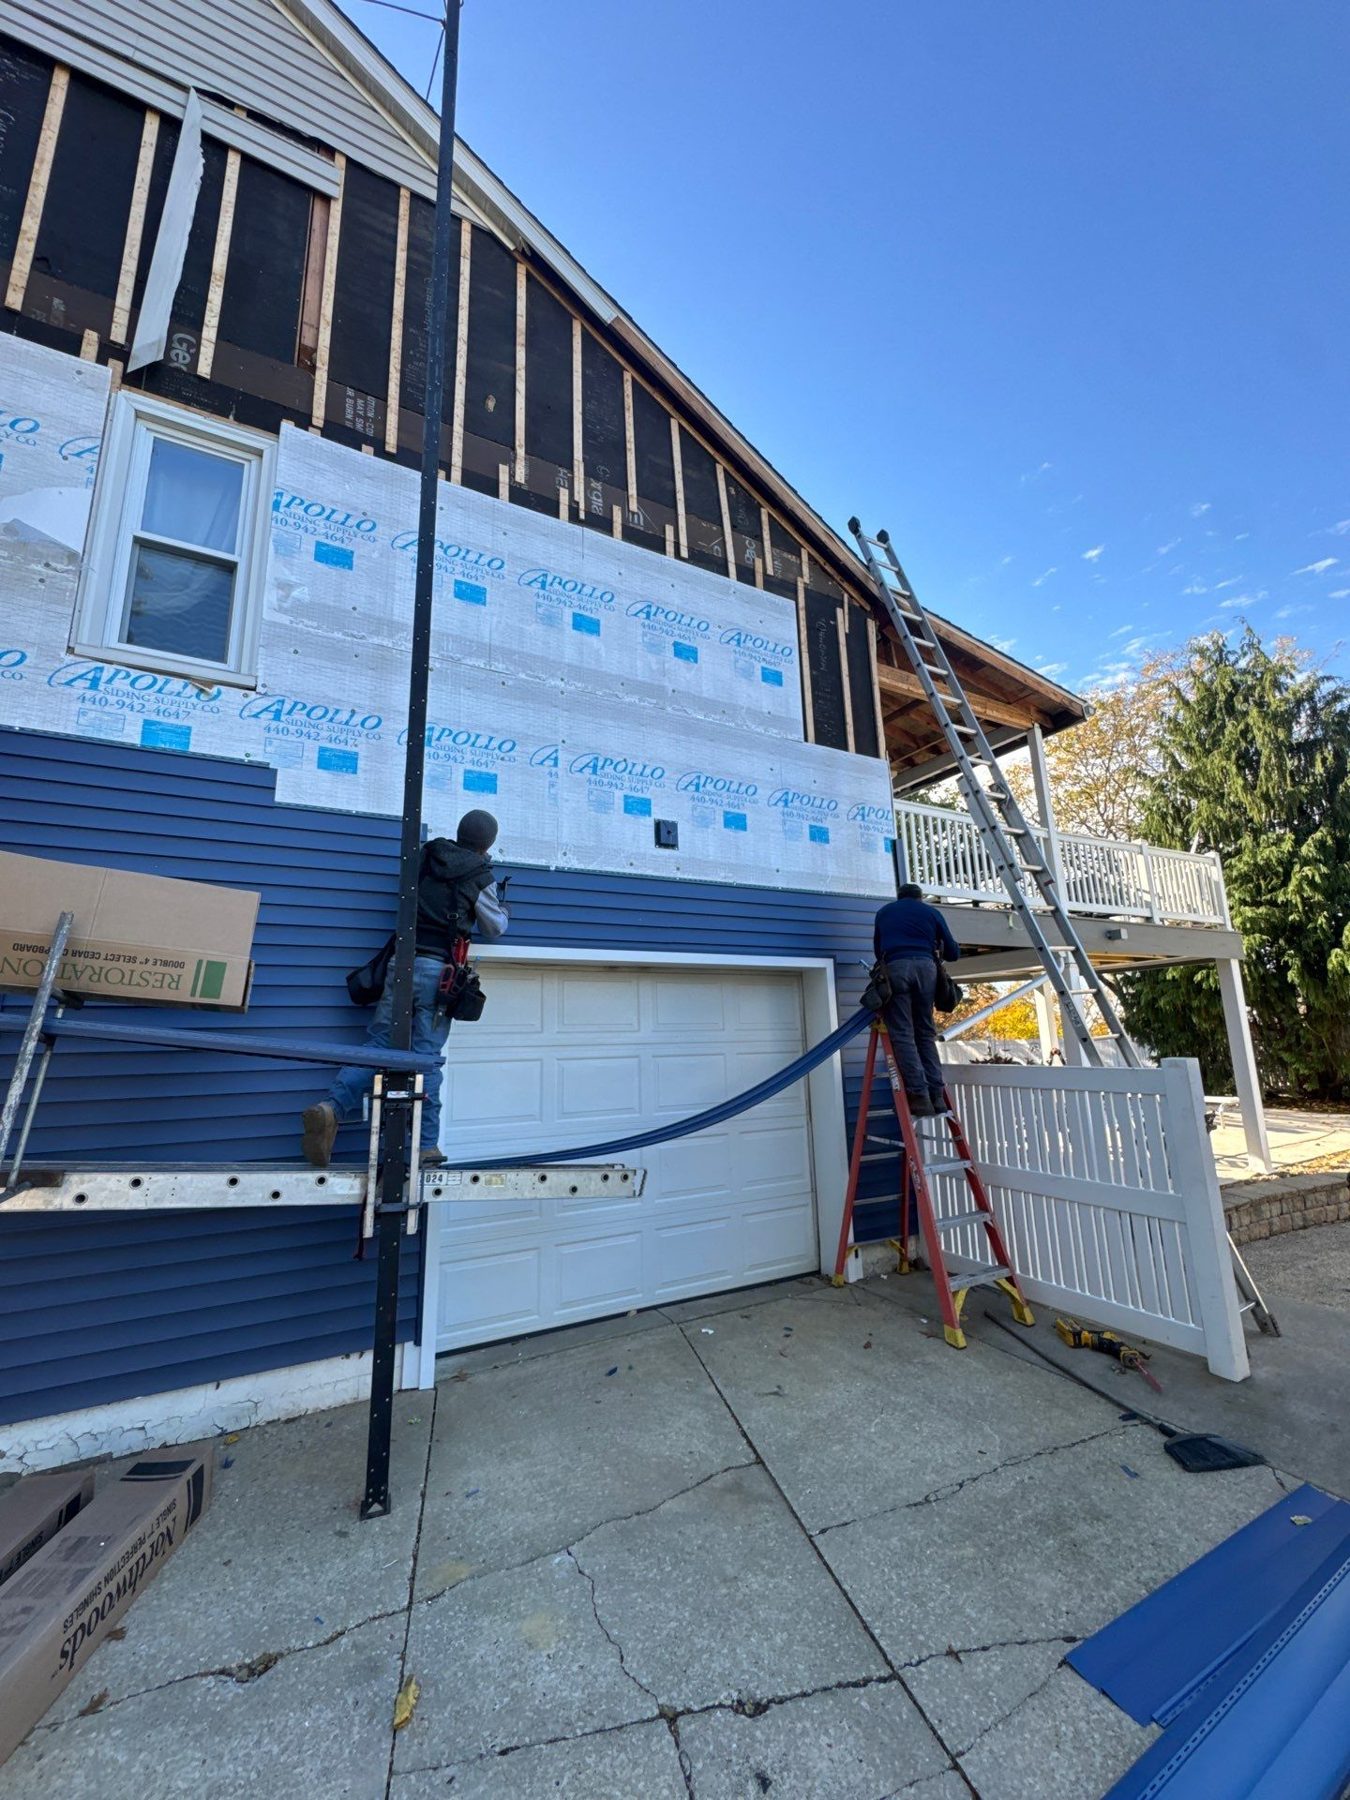
Insurance paid $136,747.92. The owner only paid their $2,233 deductible. The entire house and garage got a new roof, new siding, and new gutters.
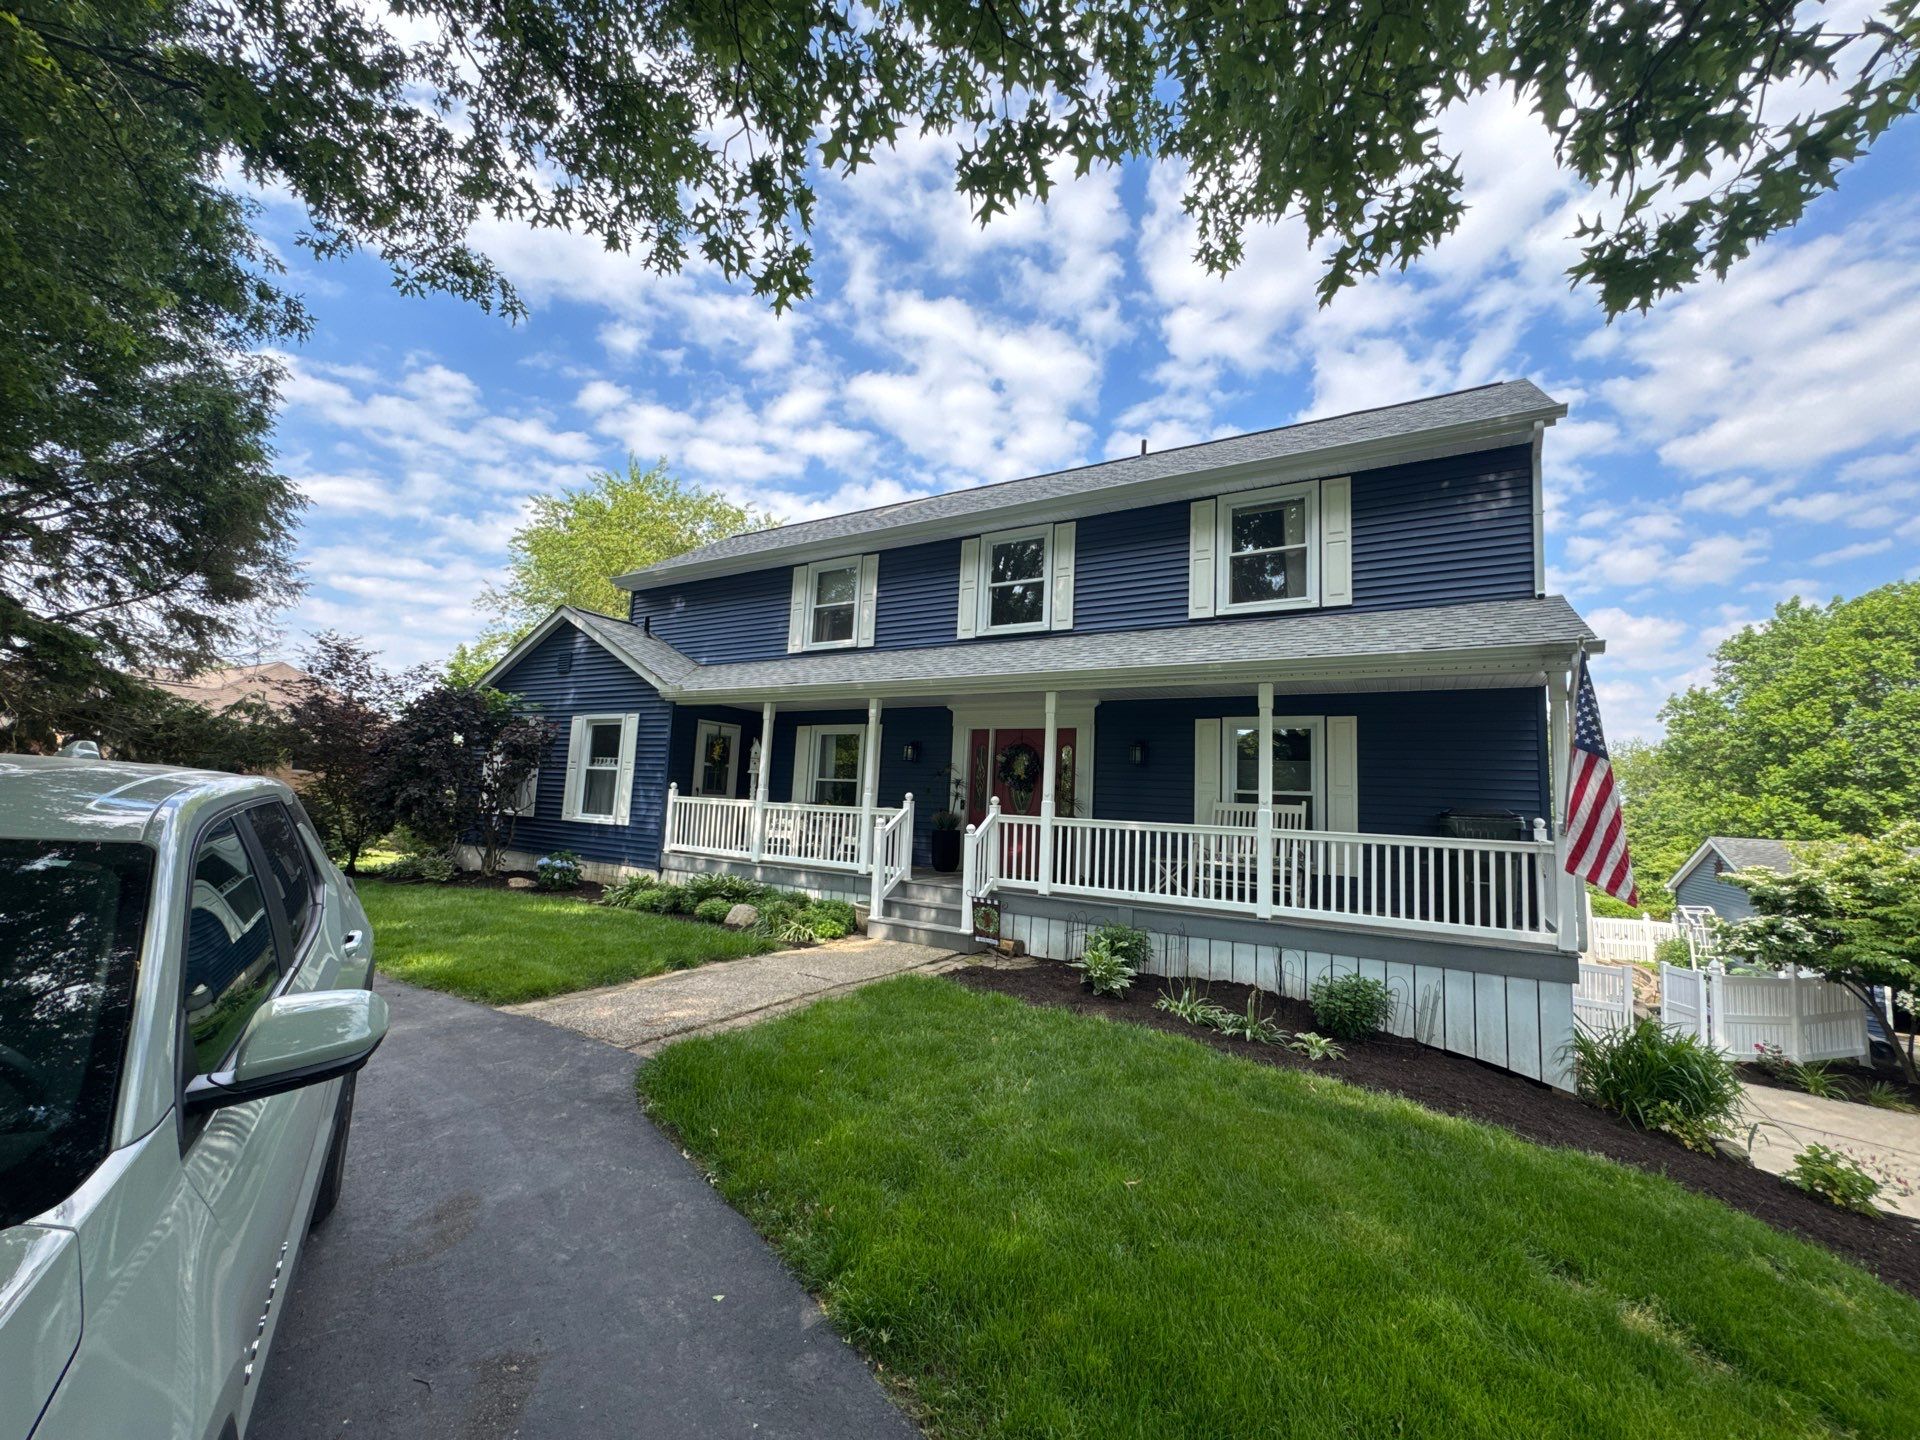
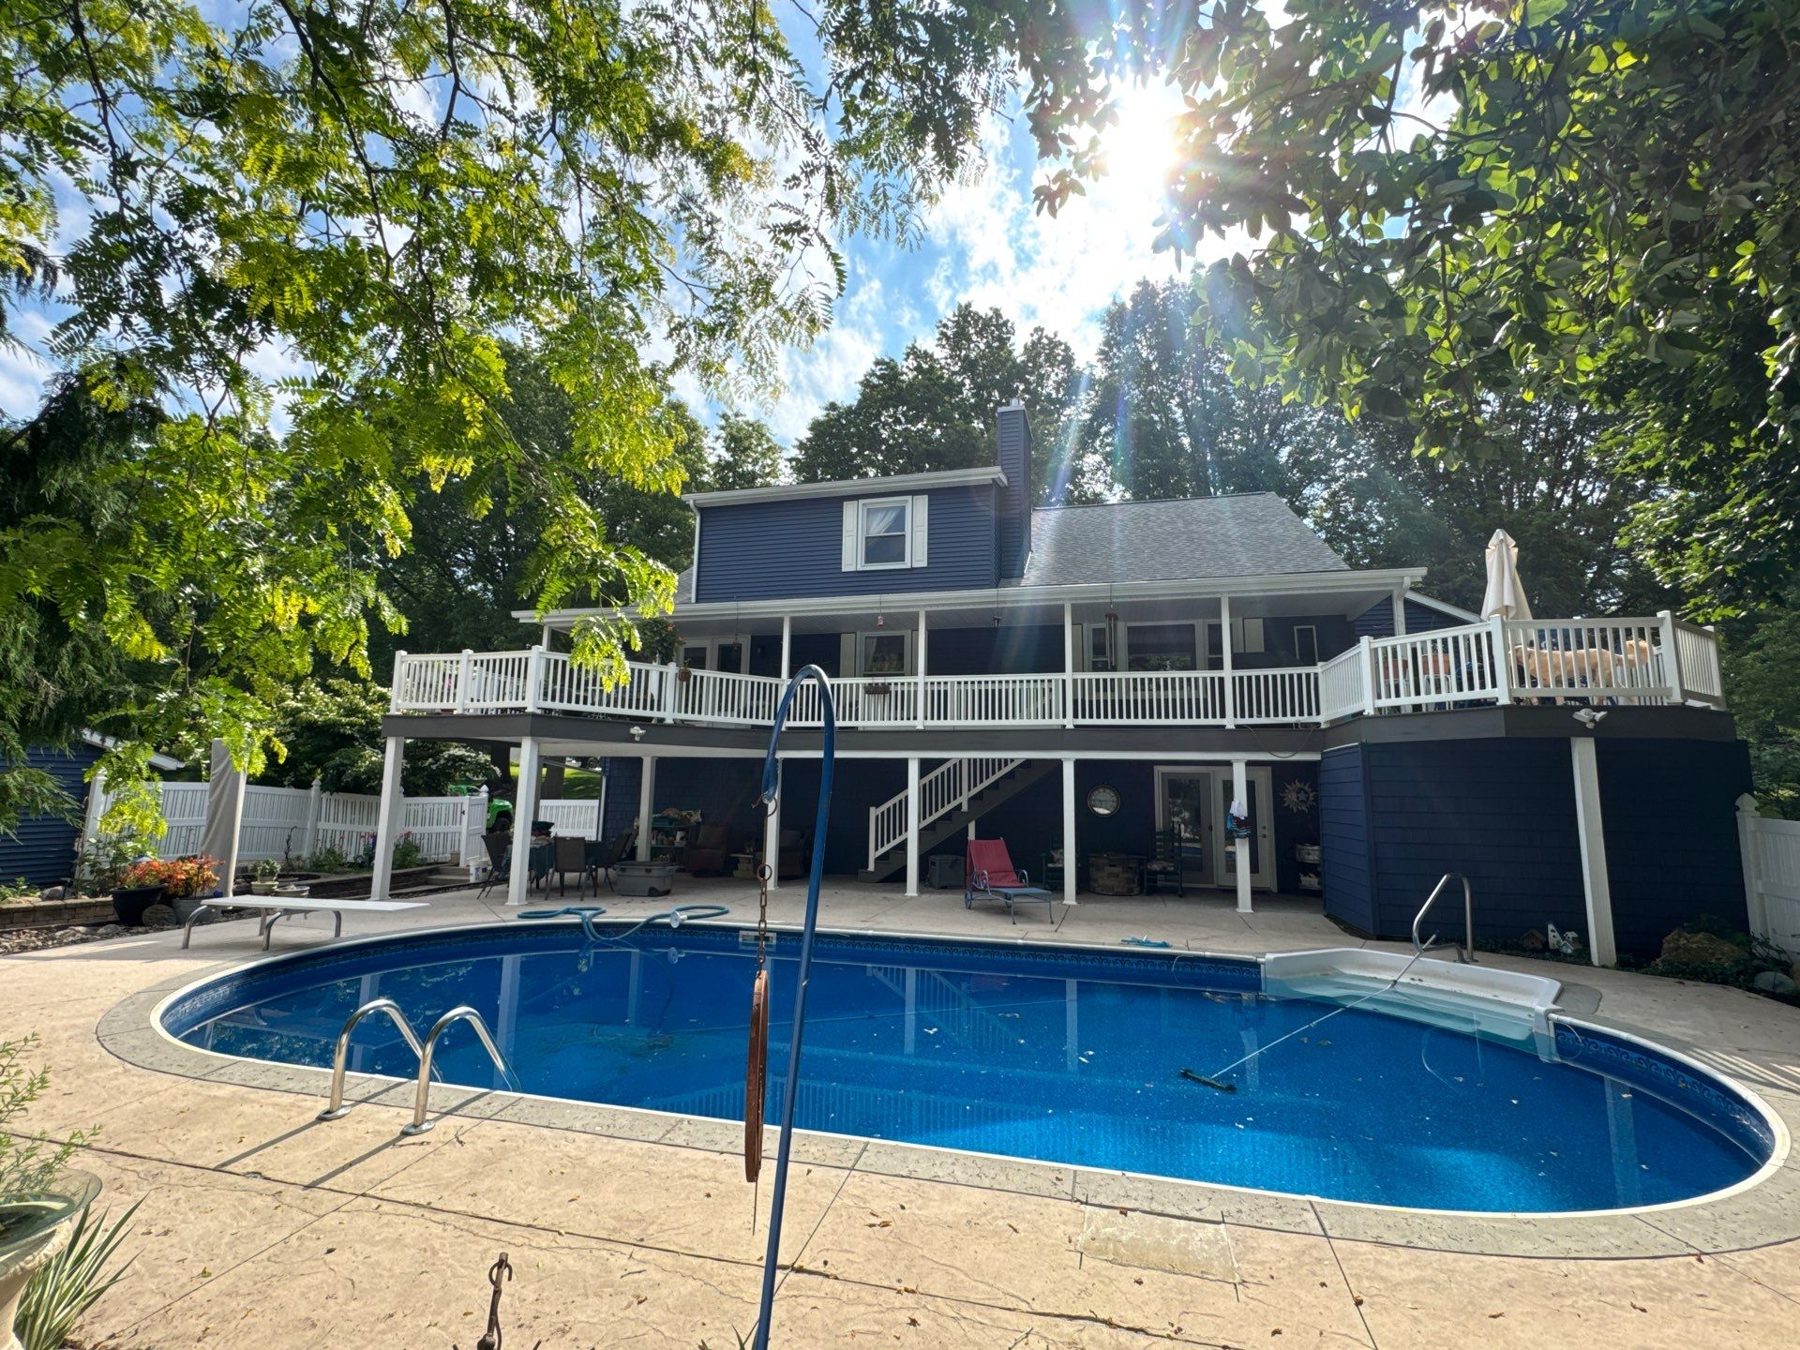
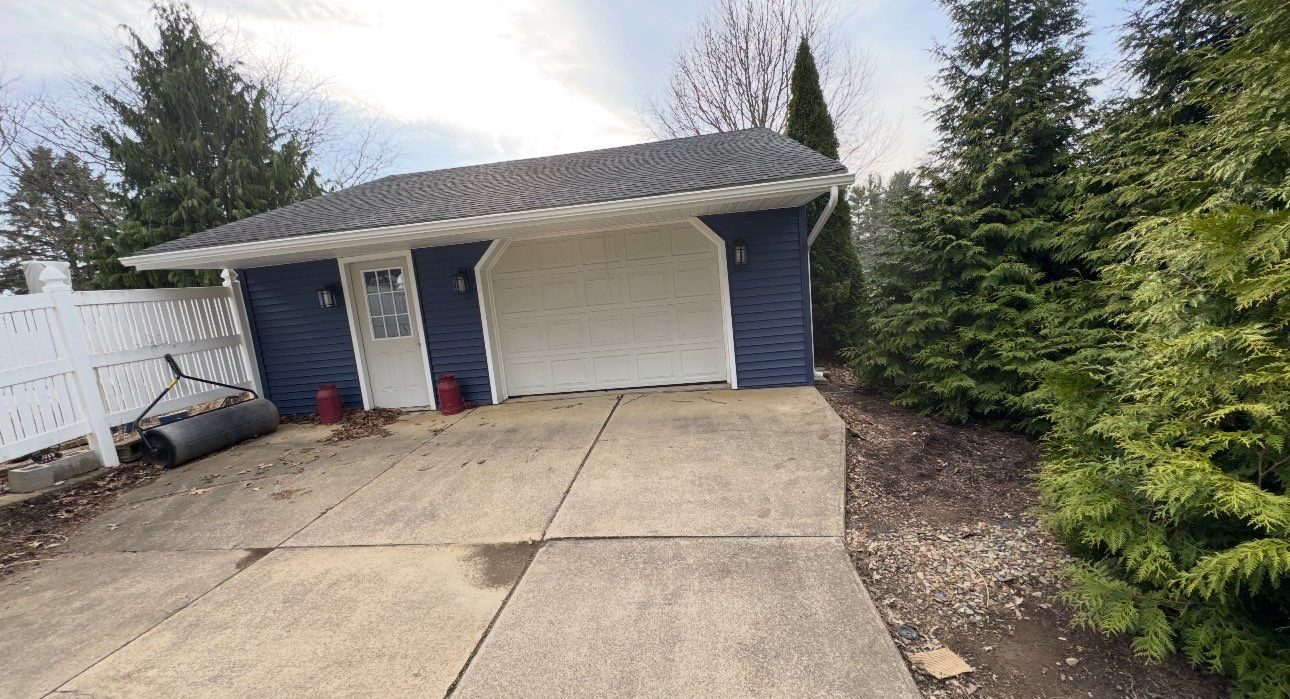
It started with one creased shingle and a few blown-off siding panels. Because the shingle and siding were discontinued, matching rules qualified the entire roof and all the siding for replacement — a $43,679.72 approved claim.


Everything homeowners ask us about winter and storm claims — answered in plain English.
How carriers decide what pays — removal vs. the interior damage.
Read the guide →How to open a claim so it closes paid.
Read the guide →The most common denial reasons — and how to avoid every one.
Read the guide →The single distinction that makes or breaks winter water claims.
Read the guide →Some policies exclude ice dams entirely — check before winter.
Read the guide →Ceilings, walls, insulation, mold — the full damage chain.
Read the guide →


Weather claims are treated differently than at-fault claims. Storm, wind, hail and ice dam losses are “acts of God” — in most cases a single weather claim doesn’t raise your individual rate the way an at-fault loss does, and rates in storm-hit areas adjust region-wide whether you file or not.
On approved claims, typically only your deductible. We handle the inspection, the paperwork, the adjuster meeting and the supplements — then do the work for the insurance-approved amount. See our financing options for deductibles too.
Most policies cover the interior water damage — ceilings, walls, insulation, flooring. The ice dam removal itself often isn’t covered. We document the interior damage and work directly with your adjuster.
That’s our specialty. Our claim team prepares supplements backed by photos, measurements and building code citations, and negotiates until the approved scope covers the work that’s actually required. Read why we built a team for this.
Commonly one year from the date of loss — sometimes less, depending on carrier and state. If you suspect damage, get a free inspection now so it’s documented well inside your window.
Reads your policy, documents to carrier standards, meets adjusters on the roof, files supplements, and releases depreciation — the claim is the project, not paperwork around it.
Every carrier — State Farm, Allstate, USAA, Farmers, Travelers and the rest. The process is ours; the logo on the check varies.
Emergency mitigation yes — it’s your policy duty and a covered cost. Restoration waits for approved scope so your deductible stays your whole cost.
Every claim topic that decides real money — explained the way we run them daily.
The exterior works as one assembly — these are the pieces that connect to this one.
The overlap is at the roof: flashing where the chimney penetrates…
Learn more →Commercial buildings need low-slope roofing and membrane repair, drainage and roof…
Learn more →Gutters control where roof water goes, and roof water is the…
Learn more →An inspection is warranted after a roof leak or water intrusion,…
Learn more →The recurring needs are inspection, repair, replacement and ventilation.
Learn more →Siding is the outer layer of a wall assembly that also…
Learn more →Insurance Claims is available across our licensed service territory in Ohio, Pennsylvania and New York. Find your city below, or call (330) 918-1018.
Free inspection, honest answer. If it qualifies, we handle everything — and you pay your deductible.
*Deductible-only applies to approved insurance claims; see claim terms.
Roof Gutter Now is based in Akron, Ohio. We are a licensed full-service exterior contractor in Ohio, Pennsylvania and New York, and crews travel for winter storm work — ice dam removal, roof snow removal and heated cables — across the northern states below. Open a state to see every city we dispatch to.
Do not see your town? Every city page lists the surrounding communities that dispatch covers — or see all service areas. Roofing, gutters and siding are offered in Ohio, Pennsylvania and New York only; other states are winter services.
Takes about 20 seconds.
